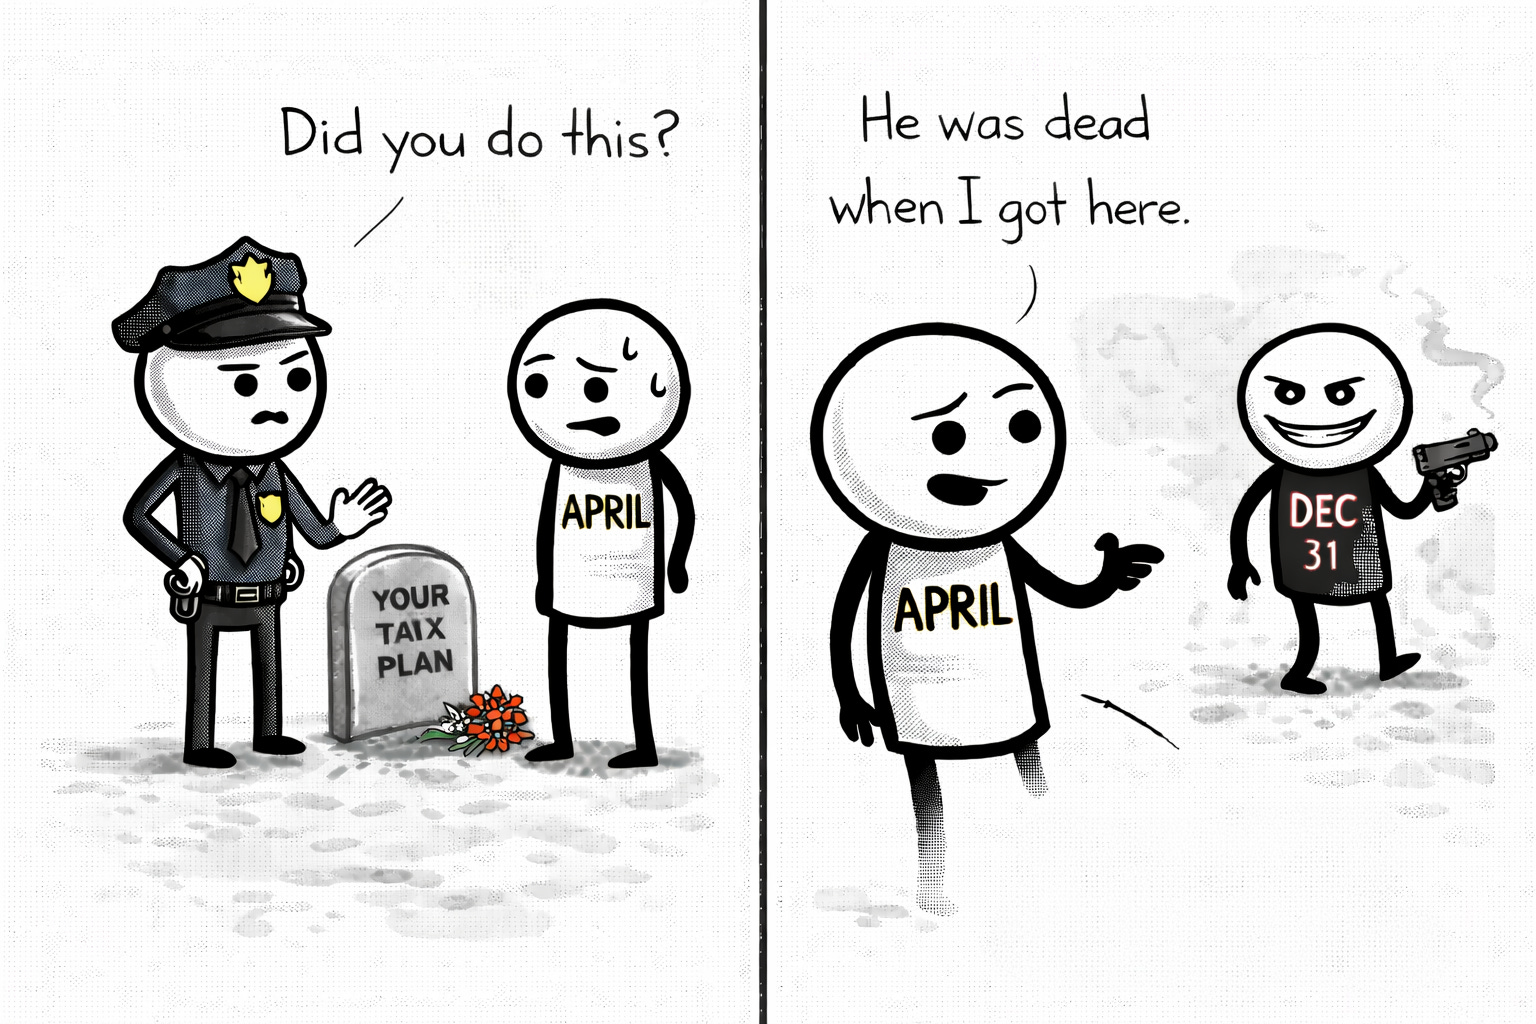
The system does something subtle every spring.
It lets April take the blame.
By the time April shows up, most people are already operating under decisions that were finalized weeks or months earlier. April feels like the deadline month because paperwork is due and payments are made. But the system quietly locks in a surprising number of outcomes long before that, while everyone is still assuming they have time.
That is what the image at the top is commenting on. April looks loud and urgent. The real locking happens earlier, without announcements, reminders, or flashing warnings.
The common belief is that April is the line in the sand.
People talk about the tax deadline as if it governs everything. If something can be done before April, it must still be flexible. If it cannot, then it must already be fixed. That mental model works just well enough to be dangerous.
The reality is that April is mostly about reporting. Many decisions are settled before that point, regardless of whether anyone has noticed.
This is how people reach April feeling surprised. Not because the rules are hidden, but because the system separates decision deadlines from filing deadlines in ways that are easy to miss.
Here is the rule underneath it all.
Different actions are governed by different clocks.
Calendar year deadlines decide whether an action belongs to one year or the next. Once December 31 passes, those actions are finalized. Filing season does not reopen them.
Tax filing deadlines control when reporting and certain contributions can still occur. Those deadlines often extend into April or later and sometimes even further with extensions.
Correction windows only exist when something was done incorrectly. They do not exist for actions that were simply postponed until they no longer existed.
What happens if something is done later instead depends entirely on which clock applied. Later might still work. Later might shift the action into a different year. Later might trigger penalties. Later might do nothing at all because the decision already hardened.
Roth conversions are one of the cleanest examples of what gets locked in early.
A Roth conversion is a calendar year event. It either happens during that year or it does not. Once December 31 passes, the year for that conversion is set.
By the time April arrives, nothing about that choice is still flexible. Filing early or filing late does not matter. The conversion either belongs to the prior year or it belongs to the current one.
If someone waits until March or April to act, doing it later does not preserve the original intent. It creates a new transaction for a new year with a new tax outcome and potentially different downstream effects.
The decision was locked in when the calendar flipped, not when the return was filed.
Required minimum distributions behave the same way.
An RMD generally must be taken by December 31. If it is missed, the system records that immediately. Nothing about April changes that fact.
Taking the distribution later stops the penalty from compounding, but it does not make the distribution timely. By the time April arrives, the status of that RMD is already fixed.
The paperwork catches up later. The decision itself did not wait.
Employer plans are where people most often assume April still has leverage.
Some plans allow funding after year end. Some do not. Some depend on when the plan existed. Some depend on the type of business.
A SEP IRA may still be opened and funded after the year ends as long as the business owner is within the tax filing deadline or extension window. In that case, April still matters.
Certain Solo 401(k) contributions may still be possible after year end depending on the structure of the business and the type of contribution. Others may already be closed if the plan did not exist by December 31.
In one case, April represents opportunity. In another, April simply confirms what was already decided months earlier.
The system is consistent. The confusion comes from assuming one deadline controls everything.
IRA contributions highlight the contrast.
Traditional and Roth IRA contributions often follow the tax filing deadline. April can still be relevant. Someone can make a prior year contribution after the calendar year ends and still have it count correctly.
Here, April actually does matter. Filing early does not eliminate the ability to contribute later. The filing deadline governs the contribution, not the calendar year.
This is why people struggle to build intuition around timing. Some things harden early. Others remain flexible well into spring.
A real scenario ties all of this together.
Someone finishes a strong income year and plans to make a few strategic moves. They file their return early because they are organized and proactive. March rolls around and they revisit their plan.
They discover that one option they assumed was still available actually locked in at year end. Another option they assumed was finished is still open. And a third item is neither open nor closed, but sitting in a correction category if it applies at all.
April did not change any of that. April just made it visible.
Nothing went wrong. No rule was broken. The system simply sorted decisions according to clocks that were running quietly in the background.
This is why April creates emotional whiplash.
People expect finality and discover nuance instead. They expect flexibility and discover permanence. The system feels inconsistent when it is actually doing the same thing it always does.
The locking does not happen when you feel pressure. It happens when the rule says it does.
The resolution here is clarity, not urgency.
Most things that get locked in before April do not represent failure. They represent timing. And timing mistakes are much easier to live with once they are understood.
If an action was governed by the calendar year, April does not change it. It only confirms it.
If an action is governed by a filing deadline, April may still matter.
If a correction window applies, it only exists if something went wrong, not if something never happened.
Once those distinctions are clear, the system stops feeling arbitrary.
By the time you finish reading, you should not be wondering what you missed. You should know exactly which parts of the year are settled and which parts are still adjustable.
April is loud. The real decisions are quiet. Knowing which is which is the difference between anxiety and confidence.
I write one of these every day, one retirement rule, explained in plain language and verified against the source. The daily email is free: subscribe here.
Disclaimer
This article is for educational and informational purposes only. It is not tax, legal, or financial advice and does not create an advisor–client relationship. Always consult appropriate professionals regarding your specific situation.