A custodian will take your money without asking whether you were allowed to send it. The deposit clears, the confirmation arrives, the balance updates, and no part of that sequence checks your earned income, your filing status, or what you already contributed at a different firm back in May. The custodian has none of that. It knows an amount arrived with a tax year attached. Everything else gets sorted out on your return, by you, later.
So an excess contribution never announces itself. It earns whatever the market gives it and looks like every other dollar in the account. People find it in September while consolidating two old accounts, or in February when a preparer adds up both custodians’ reports, or three years in when nobody caught it at all.
Excess contributions arrive in two common shapes. Either you sent more than your annual allowance, easy to do across two firms because the allowance covers all of your IRAs together, or you sent an ordinary looking amount you were never eligible to contribute, because earned income came in lower than expected or income came in higher than the Roth range allows.
Either shape carries the same consequence, an excise tax of 6% of the excess for every year it is still sitting in the account. The measurement happens at year end, and the form applies that 6% to whichever is smaller, the excess itself or the December 31 value of your IRAs of that type, so an account that lost ground produces a smaller bill than the contribution amount suggests.
The 6% disappears if you take the excess back out, along with the earnings attributable to it, by the due date of the return for the year the contribution was made for, including extensions. Removed on time, the contribution is treated as though it was never made, and the 6% never attaches for any year.
Three dates are doing different work here and they get mixed up constantly. The deadline to make a prior year IRA contribution is the April filing deadline, and it does not move for an extension. The deadline to correct a contribution does move. File an extension and you have until the extended October due date. File on time without an extension and you still get six months past the April deadline, which lands on the same October date, as long as that return went in on time. Going that route means an amended return for the year carrying the notation the instructions call for at the top, reporting the earnings and explaining the withdrawal.
The earnings come out with the excess and they are taxable for the tax year the contribution was made for. A contribution designated for one year and sent the following February still reports back to that earlier year, even though the money never sat in the account during it. Whether that means an amended return turns on whether you had already filed for that year. Fix it before you file and the earnings go on the original return. Fix it after, and the earlier year gets amended. A change in the law also removed the 10% additional tax on early distributions from earnings pulled out inside the window, which used to be the sting in the procedure.
Correct it later instead, and the 6% applies for that year end and every year end after while the excess remains. The earnings no longer have to be removed at that point, so what leaves the account is the excess alone. Whether that withdrawal is taxable depends on the account. A Roth distribution draws from regular contributions first under the ordering rules, so pulling an old excess out of a Roth is generally tax free and penalty free. A traditional contribution you deducted is a different situation, because the deduction has to come back out somewhere. And withdrawal is not the only exit. A later year in which you have unused contribution room can absorb some or all of it, and the 6% stops after the year end that absorbs it.
Two neighbors worth separating. Moving a contribution from one type of IRA to the other is a different procedure with its own timing. And excesses inside a SEP, a SIMPLE, or a workplace plan follow different correction regimes, sometimes with employer level consequences and different forms.
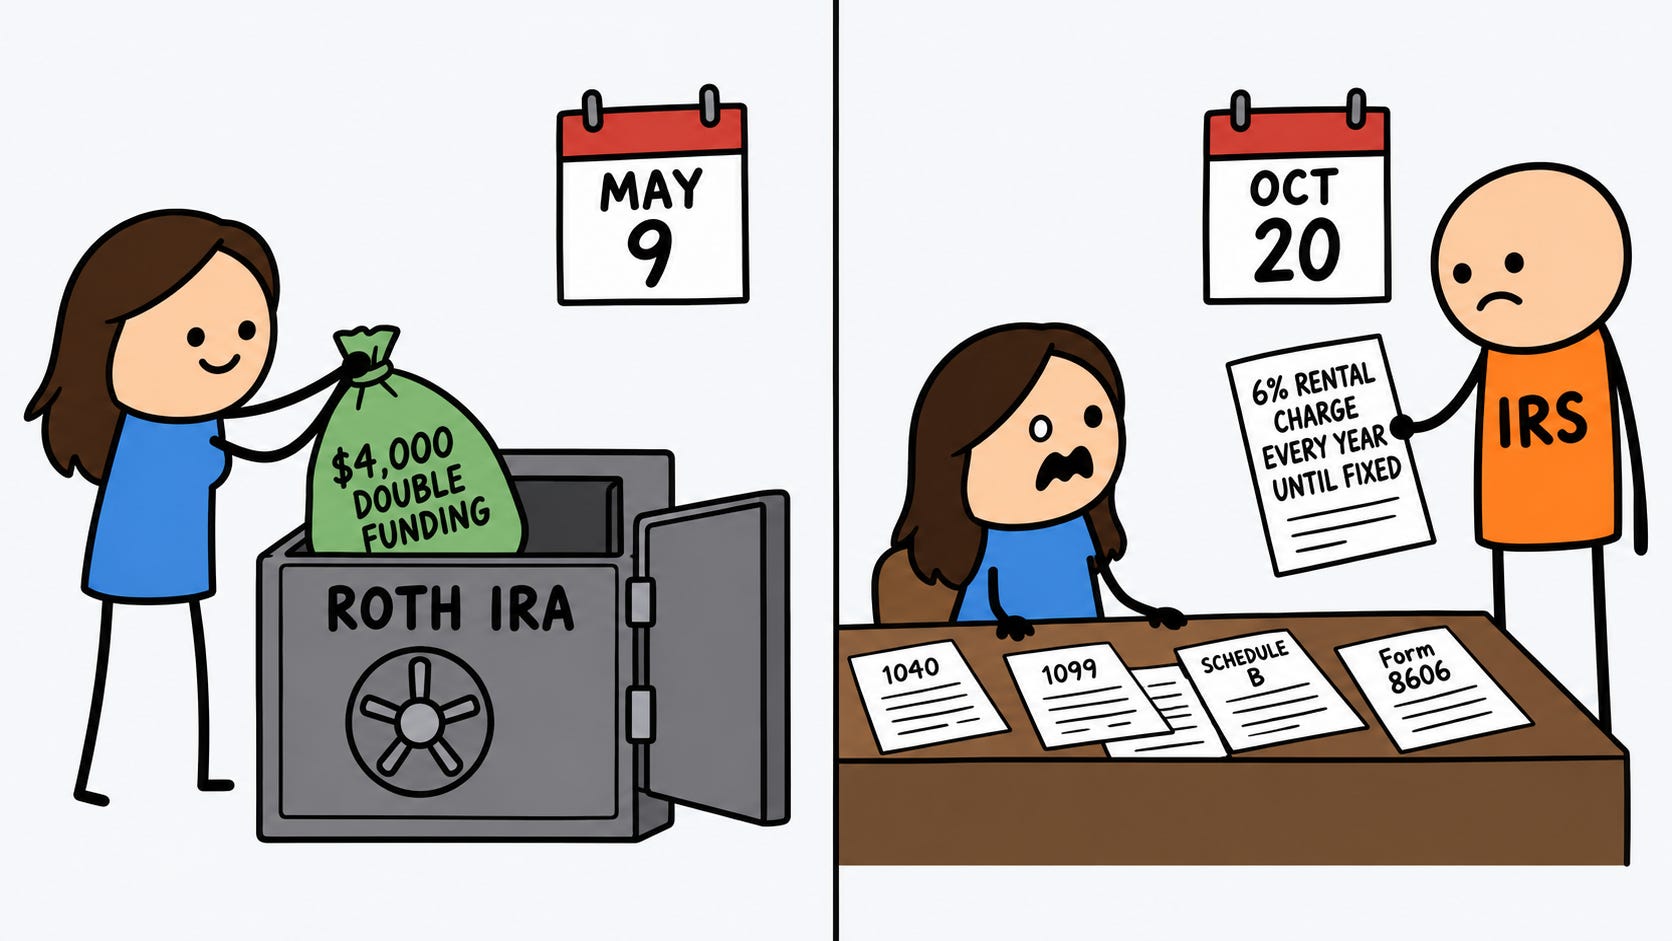
Dana is 46 and funds her traditional IRA to her full allowance on May 9. In November she opens a Roth IRA at a second firm and sends it $4,000, treating the new account as its own bucket. The annual allowance covers both accounts together, and she used it up in May, so the entire $4,000 is an excess contribution.
She files on April 9 of the following year, on time, with no extension, and nothing on the return flags it. On September 18 she consolidates both accounts at one firm and the double funding shows up on a single statement.
Because she filed on time, the correction window runs to October 15, extension or no extension. She asks the second firm for a return of the excess contribution. The earnings attributable to the $4,000 come to $226, so $4,226 leaves the Roth. The $4,000 was a contribution for the earlier year, so the $226 is income for that year, and since she already filed it, the earnings go on an amended return with the required notation and an explanation. At 46 she owes no 10% on them, and the 6% never attaches.
Now run it five days later. She finds the problem on October 20 and the window has closed. Her Roth was worth more than $4,000 at year end, so the 6% lands on the whole excess, $240, reported on the excess contribution part of the penalty form. That form belongs with a return she already filed, so it arrives with an amended one, and interest can run on the $240 from the original payment due date. The $226 of earnings stays in the account and is hers to keep. If she removes the $4,000 in November, there is no excess at the next December 31, so there is no second year of 6%.
That arithmetic is the point. The difference between Dana’s two versions is $240 and a little interest, because the amended return happens either way. A missed correction window turns a paperwork fix into a 6% annual rental charge on the excess, and the charge stops the year the excess leaves or gets absorbed. The expensive version is the one nobody finds for six years, where the same amount collects 6% at every year end until the total gets large enough to notice.
So two separate questions sit inside this. The first is whether an excess exists at all, since eligibility turns on earned income, filing status, income range, and every other IRA you own. Plenty of people worry about an excess that was never there, and walking the eligibility questions in order through a free excess contribution check settles that before anyone touches an account.
The second question is the correction, where the work is the attributable earnings figure and the year by year penalty exposure. The excess contribution fix tool runs the earnings formula on your actual account values, sorts out which correction window you are in, and lays out the steps that follow.
I write one of these every day, one retirement rule, explained in plain language and verified against the source. The daily email is free: subscribe here.
Full archive, worksheets, and search live at RetirementNewsRundown.com.
Disclaimer
This article is for educational and informational purposes only. It is not tax, legal, or financial advice and does not create an advisor-client relationship. Always consult appropriate professionals regarding your specific situation.