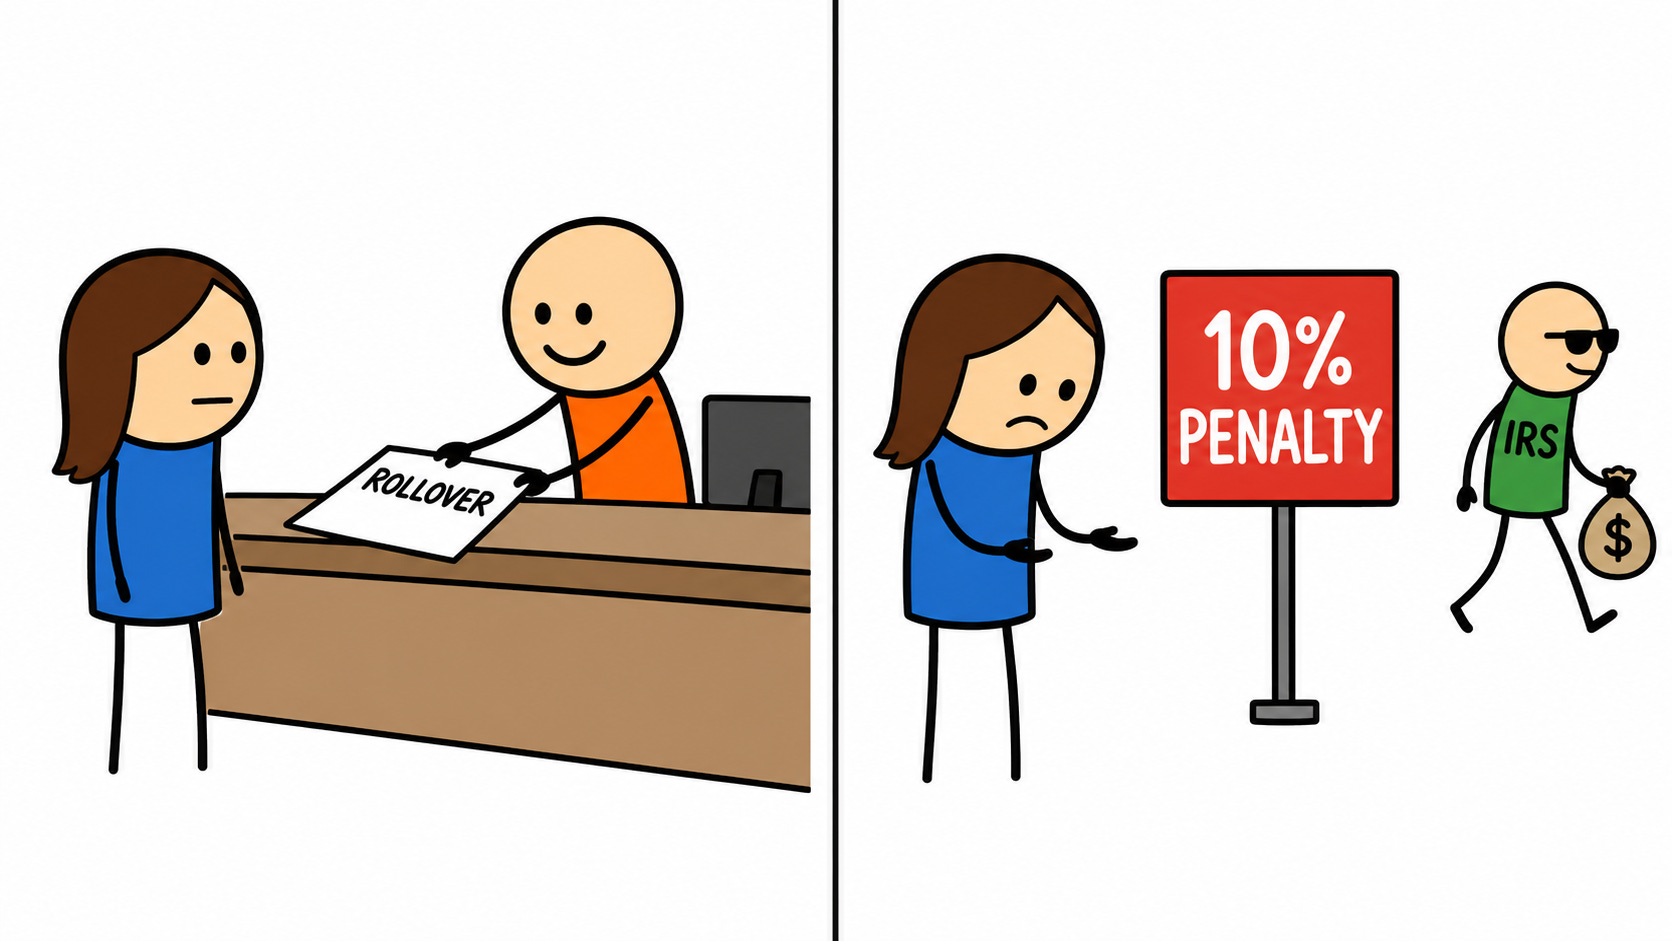
A 52-year-old widow inherits her husband's IRA. The bank rep at the IRA custodian walks her through the paperwork and recommends rolling everything into her own IRA. She signs the forms. Three years later, she needs $40,000 from the account to cover medical bills. The withdrawal generates ordinary income tax plus a 10% early withdrawal penalty because she's still under 59½. The penalty alone is $4,000. If she'd kept the IRA as an inherited IRA, the same withdrawal would have triggered the income tax with no penalty.
The 10-year drawdown rule that applies to most non-spouse beneficiaries generally does not apply to surviving spouses. As eligible designated beneficiaries, surviving spouses can usually keep an inherited IRA on life-expectancy treatment instead of draining it within 10 years. If they roll the assets into their own IRA, the account stops being an inherited IRA and follows their own IRA rules instead.
Surviving spouses face a binary choice on the inherited IRA: roll it into their own IRA, or keep it as an inherited IRA in the deceased spouse’s name. Most non-spouse beneficiaries don’t have this choice. Spouses do. The right answer depends on age, cash flow needs, and what RMD treatment helps them most.
The rollover path treats the IRA as the surviving spouse’s own from the moment the rollover completes. All standard IRA rules apply. The 10% early withdrawal penalty hits any distribution before age 59½. RMDs don’t start until the surviving spouse reaches their own RMD age. Distributions during retirement use the Uniform Lifetime Table, which produces smaller RMDs than a single life calculation.
The inherited IRA path keeps the deceased spouse’s name on the account with the surviving spouse listed as beneficiary. Distributions face no 10% early withdrawal penalty regardless of the surviving spouse’s age. RMD timing depends on whether the deceased spouse had started RMDs before death and what election the surviving spouse makes.
SECURE 2.0 added a spousal election that changed the inherited IRA math. A surviving spouse who is the sole beneficiary can elect to be treated as the deceased spouse for RMD purposes. This election can let the surviving spouse delay RMDs until the deceased spouse would have reached RMD age and use the Uniform Lifetime Table once RMDs begin. When the deceased spouse was younger than the surviving spouse, this election can delay RMDs by years compared to a standard rollover.
The penalty issue is the single biggest decision driver for surviving spouses under 59½. A rollover locks the assets behind the early withdrawal penalty until the surviving spouse turns 59½. An inherited IRA leaves the door open for penalty-free withdrawals at any age. For a younger surviving spouse who might need the money for living expenses, a child’s college, a house, or anything else before 59½, the inherited IRA path preserves access.
Switching from inherited to rollover can happen at any time. There is no deadline to make the decision. A surviving spouse can keep the IRA as an inherited IRA for a few years, then roll it into their own IRA later when the penalty issue no longer applies. The rollover can happen years after death.
Switching the other direction is not allowed. Once a surviving spouse rolls the inherited IRA into their own IRA, that decision is permanent. The IRA cannot be put back into inherited status. This is why the rollover decision deserves more thought than most surviving spouses give it.
The year-of-death RMD has its own rule. If the deceased spouse had begun RMDs before death and had not completed the year-of-death RMD, that amount still has to be distributed. The year-of-death RMD cannot be rolled over and cannot be skipped. It comes out before any rollover of the remaining balance.
A 52-year-old widow inherits her late husband’s $850,000 IRA. He was 56 at death and hadn’t started RMDs. She’s still working, but she also has two kids in college and an aging parent who may need long-term care soon. Cash flow flexibility matters more than RMD optimization right now.
She keeps the IRA as an inherited IRA. No rollover. Distributions are penalty-free at her current age. Under SECURE 2.0, she elects to be treated as her deceased husband for RMD purposes. RMDs are delayed until he would have reached RMD age, which is more than fifteen years away. She has full access to the funds without penalty if she needs them, and no required distributions in the near term.
Seven years later, she turns 59½ and her cash flow has stabilized. She rolls the inherited IRA into her own IRA at that point. The rollover gives her the standard IRA structure going forward, with RMDs starting at her own RMD age. She’s now in the same position as if she’d done the rollover at the start, with the added benefit of having preserved penalty-free access during the years she might have needed it.
Run a different scenario. A 70-year-old widower inherits his late wife’s $1.2 million IRA. She was 68 at death and hadn’t started RMDs. He’s already retired with stable income and no need for early distributions.
He elects the SECURE 2.0 spousal treatment on the inherited IRA. RMDs are delayed until his wife would have reached RMD age, which is five years away. The Uniform Lifetime Table applies once RMDs start, using his age in the distribution year. This delays RMDs compared to a rollover because his wife was younger, though the later RMD calculation still uses his age.
Two surviving spouses, two appropriate paths.
The choice between rollover and inherited IRA is permanent once made in the rollover direction. The decision deserves more thought than most surviving spouses give it in the weeks after a death.
What matters most is the surviving spouse’s age relative to 59½, their need for short-term access to the funds, and which RMD calculation produces the better outcome over time. Younger surviving spouses almost always benefit from starting in inherited IRA status. Older surviving spouses with stable cash flow often benefit from a rollover, or from the SECURE 2.0 election on an inherited IRA when the deceased spouse was younger.
The IRS gives surviving spouses flexibility that no other beneficiary gets. Using that flexibility well is worth the time it takes to think it through.
I write one of these every day, one retirement rule, explained in plain language and verified against the source. The daily email is free: subscribe here.
Full archive, worksheets, and search live at RetirementNewsRundown.com.
Disclaimer This article is for educational and informational purposes only. It is not tax, legal, or financial advice and does not create an advisor–client relationship. Always consult appropriate professionals regarding your specific situation.