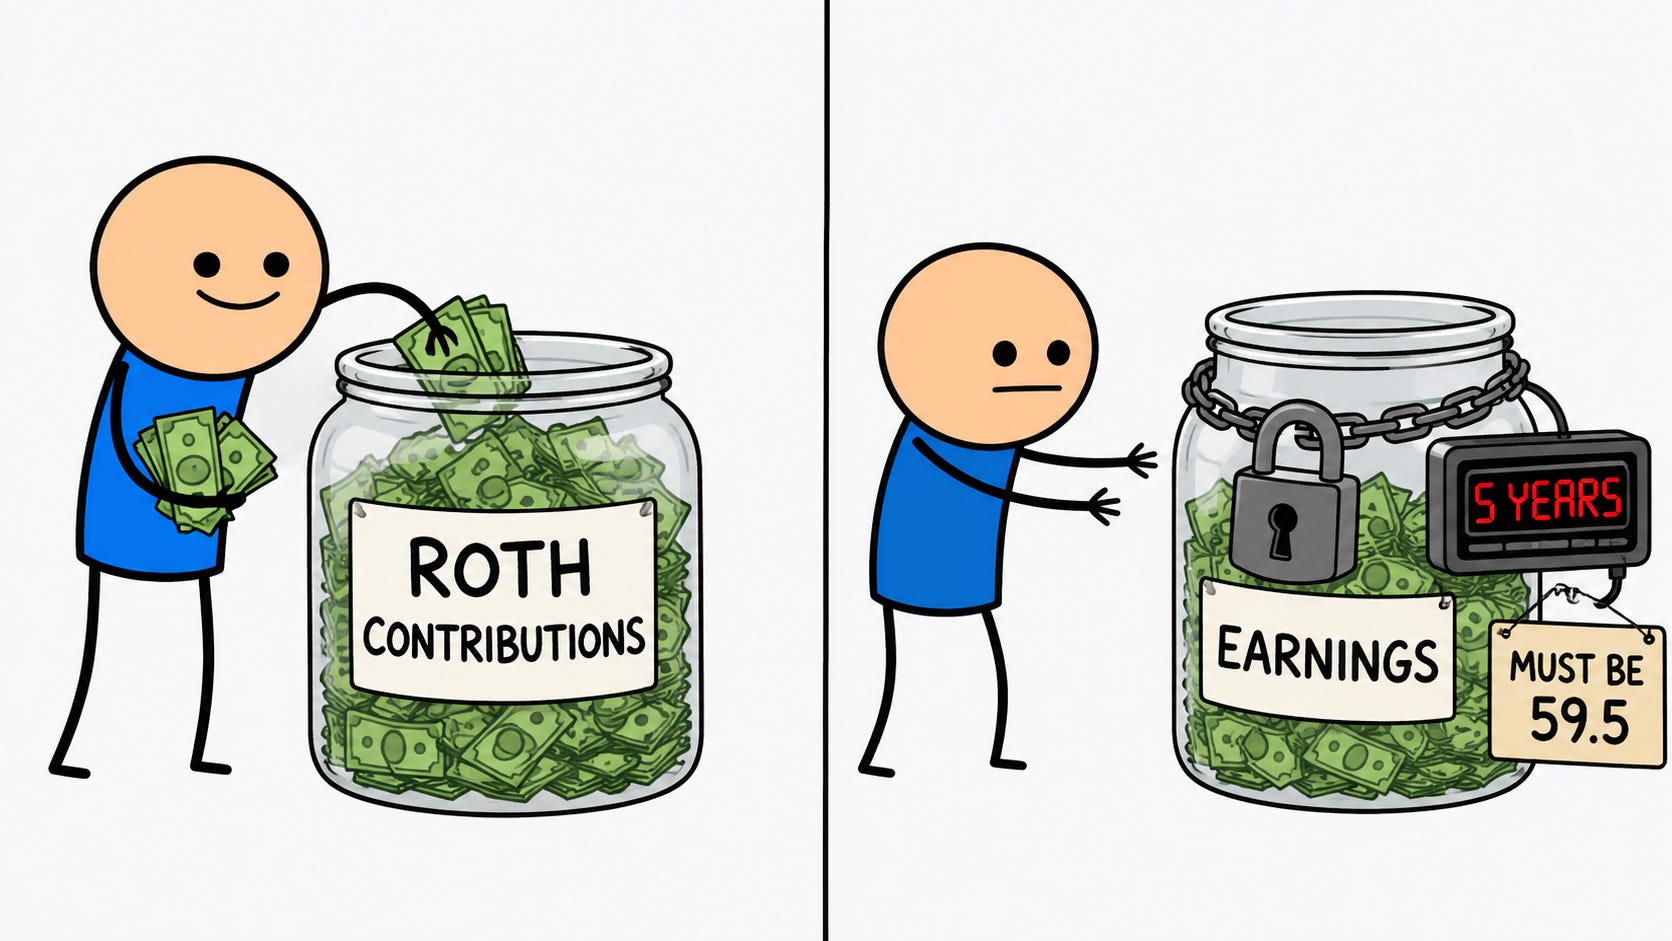
A Roth IRA gets opened, contributions go in, the account grows over time, and the assumption forms naturally. Whatever is in the account belongs to the owner, free and clear, ready to come out tax-free whenever the owner decides to take it.
That assumption breaks down in one specific corner. The growth on Roth contributions is only tax-free when the distribution counts as a qualified distribution. Anything else and the earnings portion is taxable as ordinary income, with the 10% early withdrawal tax potentially layered on top if the owner is under 59.5.
The five-year contribution clock is the rule that determines whether the qualified-distribution box gets checked.
A qualified distribution from a Roth IRA happens when two conditions are met at the same time. The first condition is that five tax years have passed since the owner’s first contribution to any Roth IRA. The second is that the owner is at least 59.5 years old, or disabled, or using up to the $10,000 lifetime limit for a qualifying first-home purchase, or the distribution is being made to a beneficiary after the owner’s death.
Both conditions have to be true at the time of the distribution. The five-year clock alone is not enough. Age 59.5 alone is not enough. Both at once is what makes the distribution qualified.
The five-year clock starts on January 1 of the tax year for which the first Roth contribution was made. A contribution made in December for that tax year starts the clock on January 1 of that same year, eleven months before the actual deposit. A contribution made by April 15 of the following year and designated for the prior tax year starts the clock on January 1 of that prior year. The clock can start before the money actually lands in the account, which is one of the few situations where the tax code works in the owner’s favor.
The clock is per person, not per account. The first Roth IRA contribution starts the clock for every Roth IRA the owner will ever hold. Once the owner’s Roth IRA five-year clock starts, opening another Roth IRA later does not create a new contribution clock.
Roth IRA distributions come out in a specific order. Regular contributions come out first. Conversion and rollover contributions come out next, on a first-in, first-out basis. Earnings come out last. This ordering matters because regular contributions can be withdrawn at any time without tax or penalty, regardless of the five-year clock. The five-year contribution clock only matters when a distribution reaches the earnings layer.
What happens if the distribution comes out before the five-year clock has cleared? The earnings portion is taxable as ordinary income. If the owner is also under 59.5 and no other exception applies, the 10% early withdrawal tax applies on top of the income tax. Regular contributions themselves are never taxed on withdrawal because they were already taxed when they went in, and the ordering rules let them come out first.
The five-year contribution clock is separate from the five-year conversion clock that applies to converted dollars. Those are different rules answering different questions. The conversion clock asks whether the 10% early withdrawal tax applies to converted principal withdrawn before 59.5. The contribution clock asks whether earnings can come out tax-free as a qualified distribution. Both clocks can run at the same time without interfering with each other.
A 45-year-old makes a first Roth IRA contribution of $7,000 in March. The contribution is designated for that tax year. The five-year clock starts on January 1 of that year.
Over the next ten years, the owner contributes $7,000 each year. By age 55, the account has $70,000 in regular contributions and roughly $30,000 in earnings, for a total balance of $100,000.
At 55, the owner withdraws $50,000 to pay for an unexpected medical situation. The ordering rules kick in. The first $50,000 out is treated as a regular-contribution withdrawal. No tax, no penalty, regardless of the five-year clock. The clock did not matter for this distribution because the distribution did not reach earnings.
At 60, the owner withdraws another $40,000. The remaining regular contributions ($20,000) come out first, with no tax or penalty. The next $20,000 reaches the earnings layer. By this point, the owner is 60 (past 59.5) and the five-year clock cleared a decade ago. Both conditions for a qualified distribution are met. The earnings come out tax-free.
If the same owner had instead taken the $40,000 at age 58, assuming no other qualifying condition or exception applied, the earnings portion would still have been taxable because age 59.5 had not been reached even though the five-year clock had cleared. Both conditions matter, not just the clock.
The five-year contribution clock is the rule that determines whether Roth IRA earnings come out tax-free. The clock matters only at the earnings layer, which most distributions never reach because of the ordering rules. Regular contributions can be withdrawn at any time, tax-free and penalty-free, regardless of how long the account has existed.
The five-year contribution clock is one of two five-year clocks that apply to Roth IRAs. The other is the conversion clock that applies separately to each converted dollar. The conversion clock asks whether the 10% early withdrawal tax applies to converted principal. The contribution clock asks whether earnings come out tax-free. Both clocks can be running at the same time, and they answer different questions.
The practical takeaway is that the clock matters for owners who plan to withdraw earnings, not for owners who plan to withdraw only the regular contributions they put in. The contribution layer is always available. The earnings layer is what the clock guards.
I write one of these every day, one retirement rule, explained in plain language and verified against the source. The daily email is free: subscribe here.
Full archive, worksheets, and search live at RetirementNewsRundown.com.
Disclaimer
This article is for educational and informational purposes only. It is not tax, legal, or financial advice and does not create an advisor–client relationship. Always consult appropriate professionals regarding your specific situation.