Most people assume an excess IRA contribution means they put in too much money. They picture someone accidentally contributing $10,000 when the limit was $7,500. That happens. But it is not the most common way excess contributions are created.
The majority of excess contributions come from people who contributed the correct amount and still ended up over the limit. The rules are more specific than “stay under $7,500.”
An IRA contribution becomes excess when it violates any of the following conditions. Not just the dollar limit. Any of them.
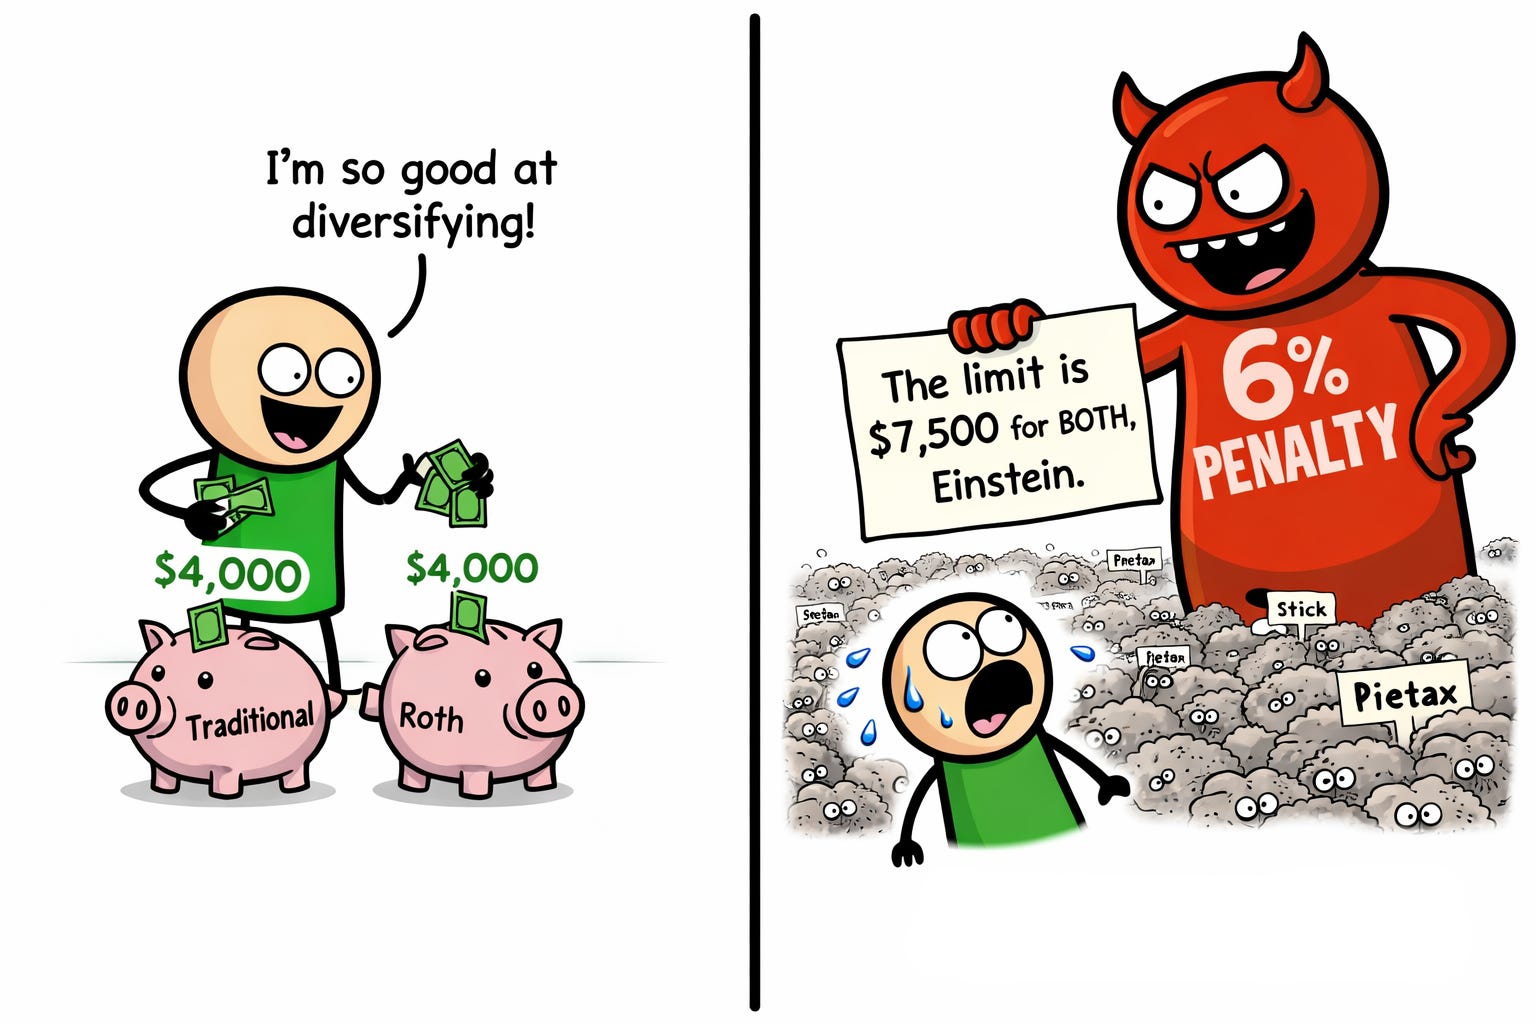
The annual contribution limit for 2026 is $7,500 if you are under 50, and $8,600 if you are 50 or older by December 31 of the tax year. That limit applies across all of your IRAs combined. Traditional and Roth. If you put $4,000 into a Traditional IRA and $4,000 into a Roth IRA, your total is $8,000. If you are under 50, you are $500 over the limit. That $500 is an excess contribution even though neither account individually exceeded the cap.
Income limits create excess contributions that have nothing to do with the dollar amount.
Roth IRA contributions are subject to MAGI phase-outs. For 2026 single filers, the phase-out range is $153,000 to $170,000 (these are estimated based on inflation adjustments). For married filing jointly, the range is $242,000 to $252,000. If your MAGI lands in the range, your allowable contribution is reduced. If it exceeds the top of the range, your allowable contribution is zero.
You contributed $7,500 to your Roth in January when your income looked fine. Then you got a bonus in November that pushed your MAGI to $168,000 as a single filer. Your allowable contribution dropped to roughly $1,500. The other $6,000 is now excess. You did not over-contribute. Your income changed the limit underneath you.
This is the most common source of excess Roth contributions, and it is almost always discovered after the fact because MAGI is not finalized until the tax year ends.
Traditional IRA contributions do not have income limits for eligibility. Anyone with earned income can contribute. But deductibility has its own phase-out if you or your spouse is covered by a workplace retirement plan. Contributing a nondeductible amount is not an excess. It is just not deductible. The contribution is still valid.
The place where Traditional IRA excess contributions happen is the earned income requirement. You must have earned income (wages, self-employment income, or taxable alimony under pre-2019 agreements) at least equal to your contribution. If you contribute $7,500 but your only income is from investments, Social Security, or rental properties, the entire $7,500 is excess. No earned income means no allowable IRA contribution.
This catches retirees who stop working mid-year. If you retired in March and earned $5,000 before leaving, your maximum IRA contribution for the year is $5,000. A $7,500 contribution creates a $2,500 excess.
Spousal IRAs have their own version of this problem. A non-working spouse can contribute to an IRA based on the working spouse’s earned income, but only if they file a joint return. If the couple files separately, the non-working spouse has no earned income to support the contribution. The full amount is excess.
This also applies when a couple files jointly but the working spouse’s income is not high enough to cover both contributions. If total earned income is $10,000 and both spouses contribute $7,500, the combined $15,000 exceeds earned income by $5,000. That $5,000 is excess.
Rollover mistakes create excess contributions that look nothing like contributions. If you take a distribution from a 401(k) and try to roll it into an IRA, but you miss the 60-day rollover window, the IRS does not treat the deposit as a rollover. It treats it as a new contribution. If the amount exceeds your annual limit (which it almost certainly does, since 401(k) balances are typically much larger than $7,500), the entire deposit is an excess contribution.
The same applies to rolling over a distribution when you have already completed an IRA-to-IRA rollover in the past 12 months. The one-per-year rule means the second rollover is not a rollover. It is a contribution. And it is almost guaranteed to be excess.
The final category is timing. IRA contributions can be made for a tax year up until April 15 of the following year. A contribution made in February 2027 can be designated for either 2026 or 2027. If you designate it for 2026 but you already maxed out your 2026 contribution, the deposit is excess for 2026. If you do not designate a year, the custodian typically applies it to the current calendar year, which may not be what you intended.
Custodians do not track your total contributions across institutions. They accept what you send and apply it to the year you specify. If you contribute $7,500 at Fidelity and $7,500 at Schwab for the same tax year, both custodians accept the deposits. Neither one flags the excess. That is your responsibility.
An excess contribution is not one mistake. It is any contribution that violates the dollar limit, the income limit, the earned income requirement, the spousal filing rules, the rollover rules, or the timing rules. Most people only know about the first one. The other five are where the problems hide.
I write one of these every day, one retirement rule, explained in plain language and verified against the source. The daily email is free: subscribe here.
Full archive, worksheets, and search live at RetirementNewsRundown.com
Disclaimer This article is for educational and informational purposes only. It is not tax, legal, or financial advice and does not create an advisor-client relationship. Always consult appropriate professionals regarding your specific situation.