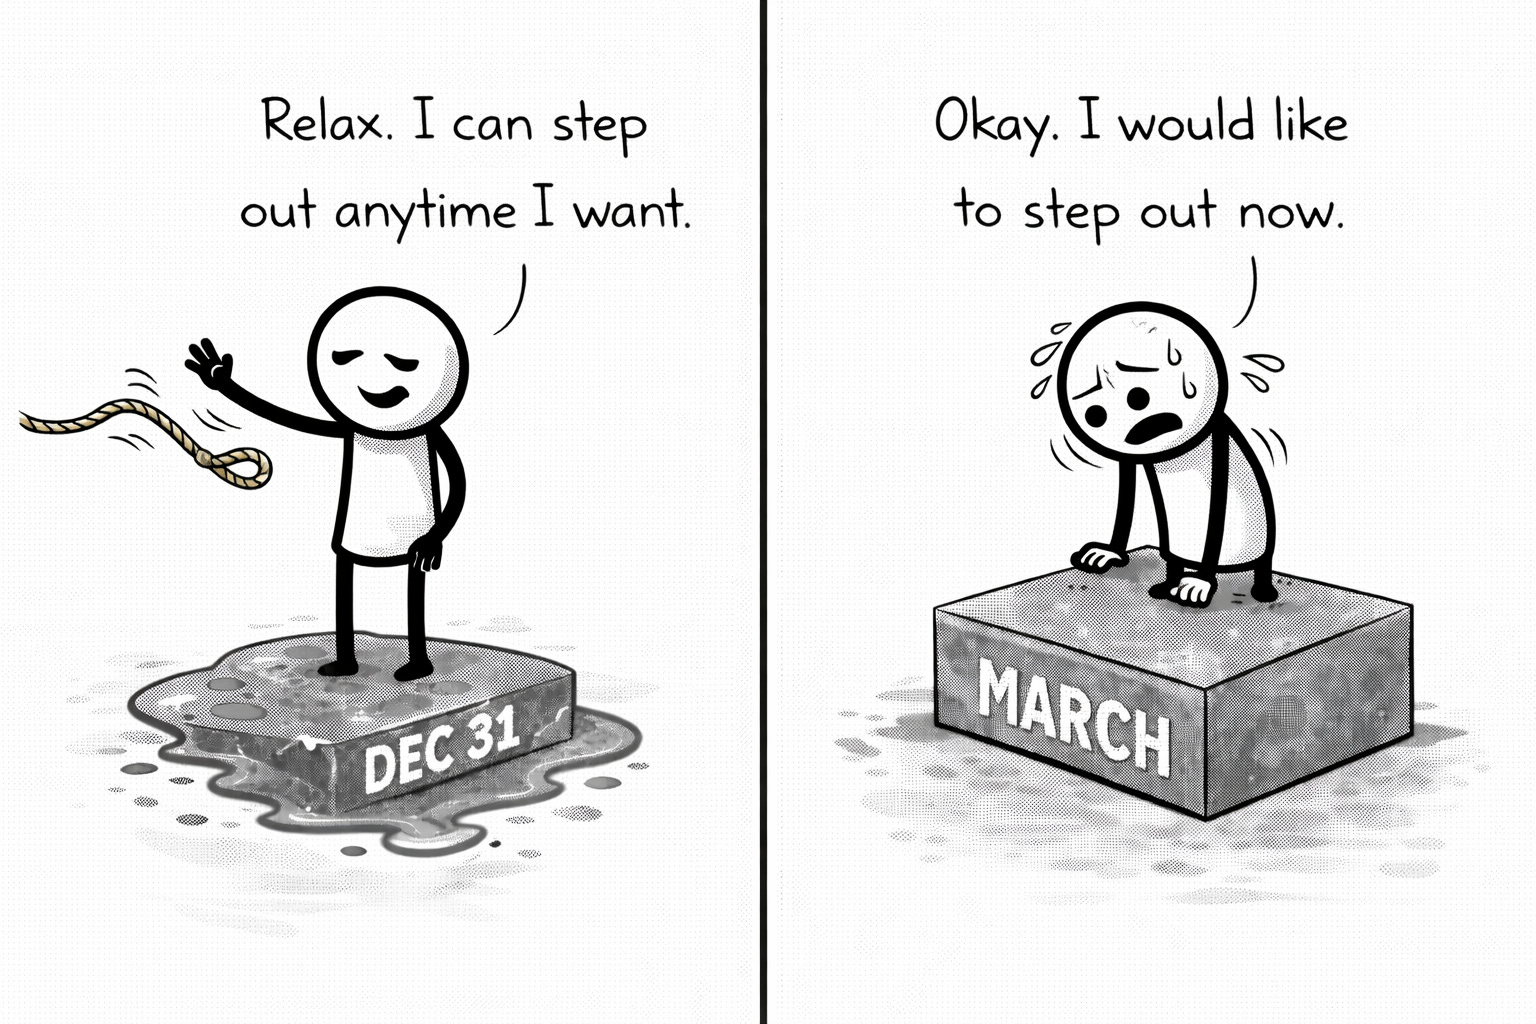
By the time March rolls around, most of the decisions already feel made, even though no one remembers actually making them.
“I don’t need to decide yet.”
That sentence feels responsible. Thoughtful. Almost disciplined. There is no rush. The option is flexible. The system allows time. So people wait, not because they are careless, but because waiting feels like the safer, more informed move.
Nothing pushes back. No alerts fire. No forms bounce. The choice still appears to be sitting there, patiently available whenever life calms down enough to deal with it.
Until one day, usually in March, someone asks whether they can still do the thing they have been planning to do all along. That is when they find out the choice did not disappear loudly. It simply stopped being flexible while no one was watching.
Here is the rule that makes this happen.
Some choices are flexible only within a specific window. Others look flexible because the consequences arrive later. And some are flexible only if you are paying attention to which clock governs them.
Calendar year rules decide whether an action belongs to one year or another. Once the calendar flips, the flexibility is gone, even if nothing feels different yet.
Tax filing deadlines control reporting and certain contributions. Those feel forgiving because extensions exist and paperwork can lag behind reality.
Correction windows exist only when something was done incorrectly. They do not apply to things that were postponed out of existence.
The mistake people make is assuming flexibility lives forever unless something actively shuts it down. In reality, flexibility often expires quietly at a date no one is thinking about because nothing happens on that date that feels urgent.
What happens if something is done later instead depends entirely on which rule applied. Sometimes later works. Sometimes later changes the year. Sometimes later triggers penalties. Sometimes later means the option is simply gone.
Roth conversions are a classic example of a flexible choice that is not flexible for very long.
People like Roth conversions because they feel optional. You choose when to do them. You choose how much. You can run projections. You can wait for better information.
All of that is true, until December 31.
A Roth conversion either happens during a calendar year or it does not. If it is done in March, it belongs to the current year, not the prior one. There is no filing deadline extension that reopens the prior year. There is no correction window because nothing was done wrong. The choice was simply not exercised in time.
Doing it later does not preserve the original intent. It creates a different transaction with different tax consequences, potentially different Medicare premium implications two years later, and a different interaction with other income.
The flexibility was real, but it had an expiration date that was easy to ignore.
Required minimum distributions show the same pattern from the opposite angle.
People know they have to take them. They also know the penalties exist. But because the reporting happens later, the urgency does not feel immediate.
If an RMD is missed at the end of December, the flexibility ends right there. March does not reopen the window. The distribution can still be taken, but it is late. Penalties may apply unless relief is granted. The action is no longer optional. It is now damage control.
Later does not undo the miss. It only limits how bad it gets.
Employer plans add another layer where flexibility depends on details people rarely separate clearly.
Some contributions can be made after year end. Some cannot. Some depend on when the plan existed. Some depend on the type of business.
A SEP IRA can feel almost magically flexible. A business owner can open it for the first time in March and fund it for the prior year if they are within the filing deadline or extension window. The flexibility is real and generous.
Solo 401(k) plans behave differently depending on structure. A sole proprietor has more flexibility now and may still establish and fund after year end. An S corporation owner generally does not have that same freedom for employee deferrals. The calendar matters more there.
The choice feels flexible until the moment it is not, and the moment it stops being flexible depends on facts people often do not realize are relevant.
Doing it later might still work. Or it might convert the move into a current year action. Or it might erase the option entirely. The same delay produces very different outcomes depending on which rule applied.
Here is a concrete scenario that plays out every year.
Someone has a strong income year. In November, they plan to make a retirement move. December is chaotic. January arrives with good intentions. By March, they finally sit down and ask whether they can still do what they planned.
If the action was governed by a tax filing deadline, the answer might be yes. If it was governed by the calendar year, the answer is already no, even though the question is being asked politely and in good faith.
Nothing failed. No rule was broken. The system simply stopped waiting.
The confusion comes from the delay between decision, reporting, and consequence. Flexibility disappears at the decision point, not the paperwork point.
This is why people feel blindsided.
The system does not announce when flexibility expires. It just changes the nature of the choice. Optional becomes fixed. Strategic becomes reactive. Planning becomes explaining.
Once you understand that, a lot of the fear evaporates.
The resolution here is not urgency. It is clarity.
Not every flexible choice is meant to stay flexible indefinitely. Some are meant to be exercised within a window and then resolved. The problem is not waiting. The problem is waiting without knowing which clock is running.
If a choice is governed by a calendar year deadline, flexibility ends when the year ends, even if the consequences show up later.
If a choice is governed by a filing deadline, flexibility may extend into spring or beyond.
If a correction window applies, it only exists if something went wrong, not if something never happened.
Once those distinctions are clear, the system stops feeling unfair. It starts feeling predictable.
By the time you finish reading, you should not feel rushed or behind. You should feel oriented. You now know why some options quietly stiffen over time and why asking the question later does not always mean the answer will be the same.
Flexibility does not vanish randomly. It expires on schedule.
I write one of these every day, one retirement rule, explained in plain language and verified against the source. The daily email is free: subscribe here.
Disclaimer
This article is for educational and informational purposes only. It is not tax, legal, or financial advice and does not create an advisor–client relationship. Always consult appropriate professionals regarding your specific situation.