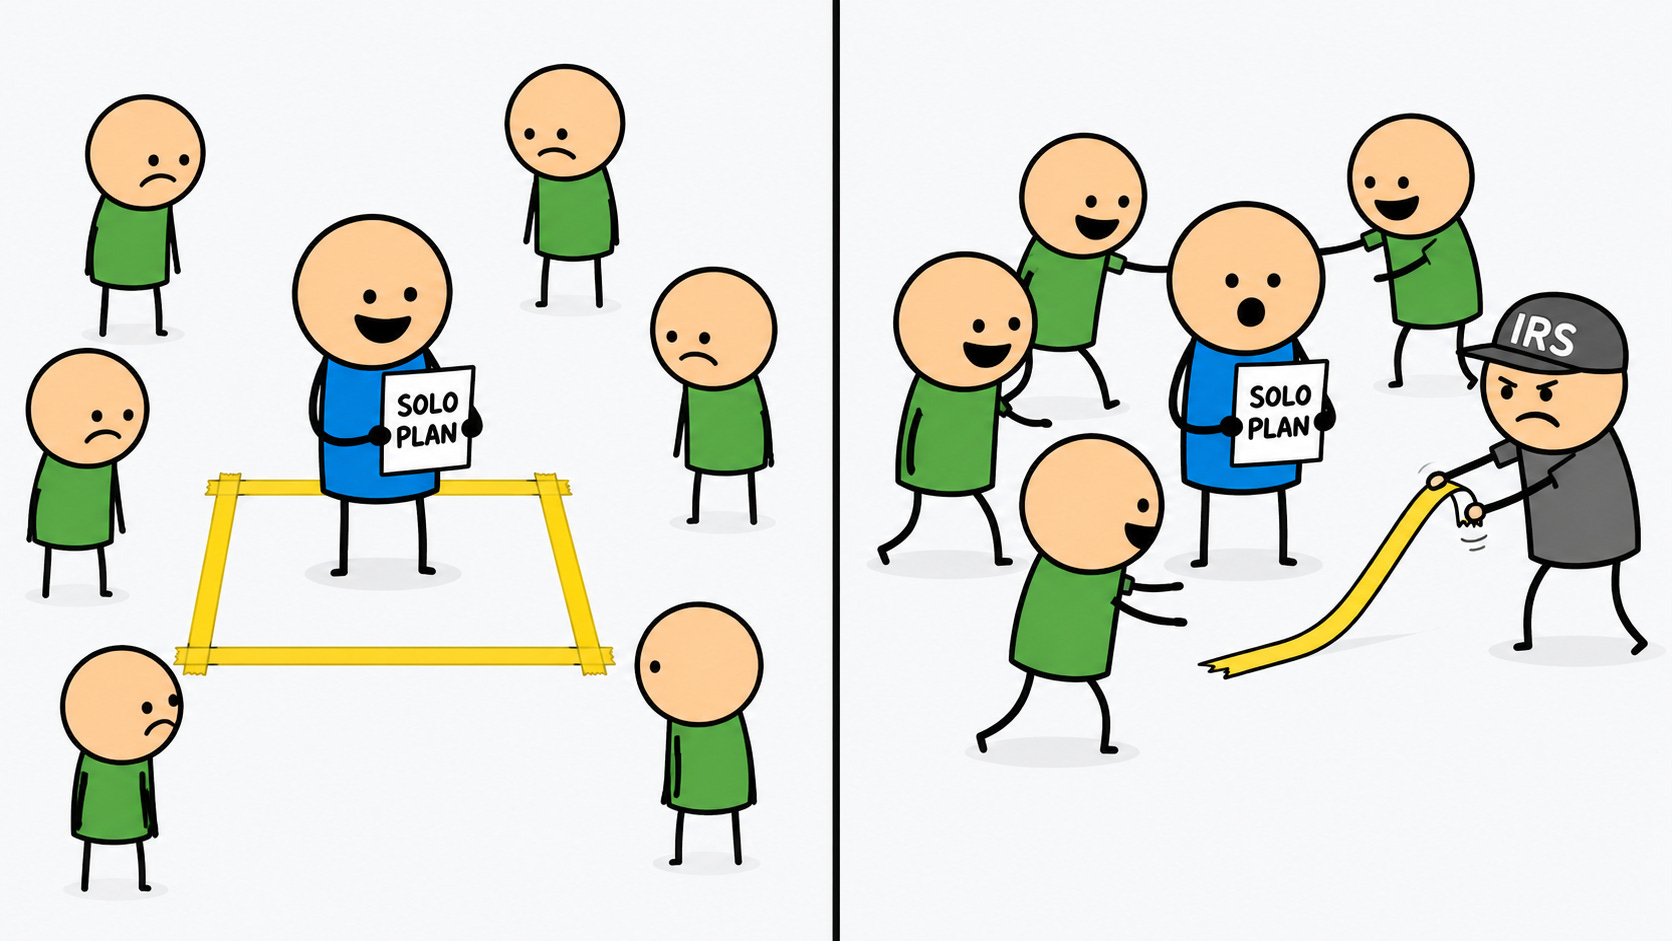
A business owner with two separate companies thinks of them as two separate worlds for retirement planning. One company has employees, the other does not, and the owner sets up a solo plan under the company without employees, expecting the simple treatment that comes with that label. The plan administrator does not push back. The custodian does not push back. The arrangement looks clean from inside the owner’s office.
The tax code looks at it differently. When the same person owns enough of two or more businesses, the IRS treats those businesses as a single employer for retirement plan testing, regardless of how they are organized on paper. The rule is called the controlled group rule, and it exists for one reason. It stops an owner from carving off a slice of the company into a separate entity and running a plan that ignores the rest of the workforce.
The controlled group rules aggregate related businesses for plan testing purposes. When two or more businesses meet the ownership thresholds, every employee of every business in the group is treated as employed by a single employer when the plan runs its coverage and nondiscrimination tests. The plans themselves can stay separate. The testing cannot.
Three main configurations trigger a controlled group. A parent-subsidiary group exists when one business owns at least eighty percent of another. A brother-sister group exists when the same five or fewer individuals, estates, or trusts own at least eighty percent of each business and, using only each owner’s identical ownership in each business, own more than fifty percent. A combined group is the third configuration, formed when a parent-subsidiary group and a brother-sister group are linked through common ownership.
Separate from the controlled group rules, there is the affiliated service group concept. That set of rules targets professional and service-oriented businesses that share ownership and service relationships in ways the basic controlled group tests do not always catch. A medical or legal practice with associated entities is a common setting where affiliated service group analysis becomes necessary.
Attribution rules sit on top of all of this. Ownership held by a spouse may be attributed unless specific exceptions apply, and ownership held by an entity may be attributed back to the owners of that entity. Family attribution can extend to children, grandchildren, and parents in certain situations. A business that looks separately owned on a corporate chart can become part of a controlled group once attribution is applied.
What happens when the controlled group is triggered. The plan must pass its coverage test based on the entire employee population of the group, not just the population of the company sponsoring the plan. A solo 401k under one company with no employees is not actually a solo plan if the same owner has another company with employees that fall under the same controlled group. Coverage testing, nondiscrimination testing, top-heavy aggregation, and the overall contribution and benefit limits all run as though the group were one employer.
What happens if you do this later instead. The controlled group does not stop existing because the owner did not realize it was there. The plan continues to be tested against rules it cannot pass while ignoring half the workforce. The result is a qualification failure that may require correction for the employees who were improperly excluded, often through IRS correction procedures. Depending on the facts, that can mean qualified nonelective contributions for missed deferral opportunities, missed matching or employer contributions, retroactive plan changes, or some combination of paperwork and money. Naturally, the money part is the one everyone remembers. The longer the failure runs, the more expensive the correction becomes, because the correction generally requires making contributions for prior years to bring the excluded employees into the position they should have been in.
A business owner runs two LLCs. The first is an operating company with ten employees on payroll. The second is a real estate management entity with no employees, only the owner. The owner sets up a solo 401k under the real estate LLC, on the theory that the entity has no employees and qualifies for one-participant treatment.
The owner owns one hundred percent of both businesses. That ownership crosses both the controlling interest threshold and the identical ownership threshold, and with only one owner, the five or fewer individuals test is automatically met. The two LLCs are a brother-sister controlled group.
The solo plan must now consider all ten employees of the operating company for coverage testing. Either the plan covers an adequate cross-section of the controlled group’s combined workforce, or it must be amended, terminated, or restructured. If the failure has been running for years before anyone catches it, the correction generally requires contributions for the excluded employees for those prior years.
The controlled group rules exist for a reason that is hard to argue with. Without them, an owner could put a small slice of the business into a separate entity and use that entity to run a plan that benefits the owner while ignoring the rest of the workforce. The rules close that door through ownership tests, not through paperwork the owner chooses to file, which is why so many owners stumble into a controlled group without knowing.
What truly matters is recognizing when the rules might apply. If the same individual, the same small group of people, or the same family owns substantial stakes in more than one business, controlled group analysis is part of the picture. Spousal and family attribution makes the analysis broader than it looks on a corporate chart. Service-related businesses bring affiliated service group analysis into the mix.
A controlled group on its own is just a fact about ownership. The damage comes from running a plan that ignores the rules a controlled group triggers. A plan tested against the right population is fine. A plan tested against the wrong population is heading toward a correction that gets bigger the longer it waits. Asking the question before the plan is set up is far cheaper than asking it after.
I write one of these every day, one retirement rule, explained in plain language and verified against the source. The daily email is free: subscribe here.
Full archive, worksheets, and search live at RetirementNewsRundown.com.
Disclaimer This article is for educational and informational purposes only. It is not tax, legal, or financial advice and does not create an advisor–client relationship. Always consult appropriate professionals regarding your specific situation.