Filling out a beneficiary form feels like a formality. A person writes down their children’s names, splits the account evenly among them, and moves on, assuming the job is done. Buried in that form, though, is a choice most people never notice, usually a small box or a line asking whether the designation is per stirpes or per capita. Those two Latin terms decide something the person may care about deeply, what happens to a beneficiary’s share if that beneficiary dies before the account owner does. Get the choice wrong, or skip it entirely, and an entire branch of the family can be cut out of the inheritance by accident.
Both terms speak to the same single question. If one of the named beneficiaries dies before the account owner, where does that beneficiary’s share go? On many retirement-account forms, the choice works like this: per stirpes keeps a deceased beneficiary’s share within that person’s family branch, while the default or per capita treatment divides that share among the surviving beneficiaries. The account agreement and beneficiary form control the exact result, so the wording has to be checked rather than assumed, but the common structure is worth understanding because it is what most forms follow.
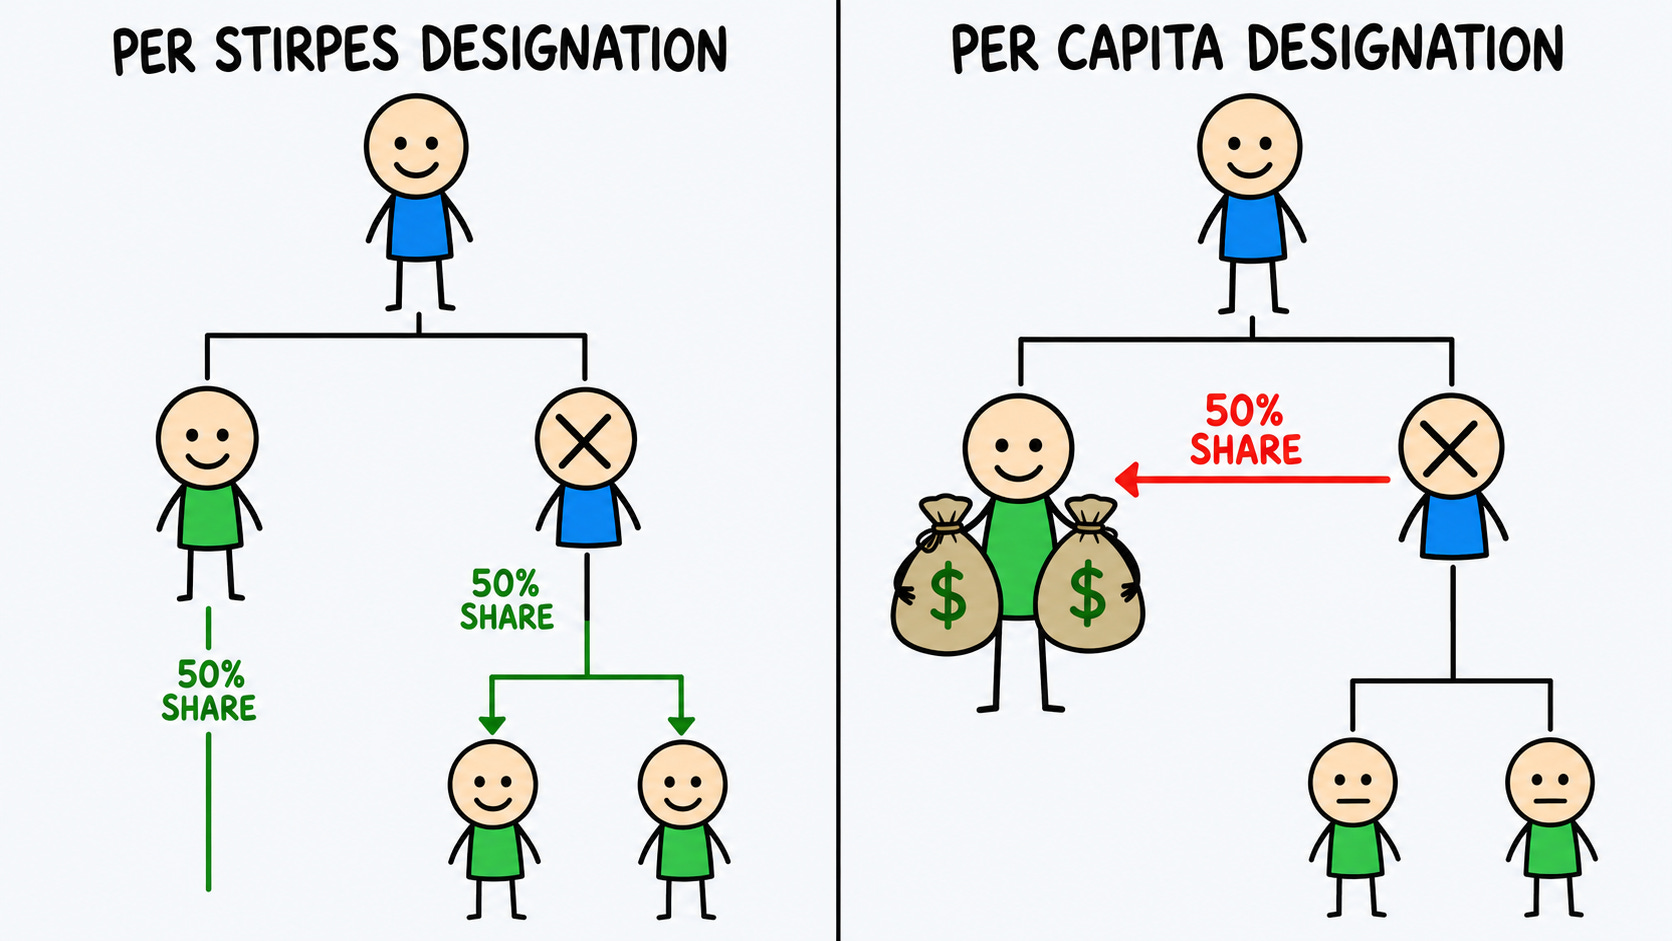
Per stirpes means by the branch. Under a per stirpes designation, if a beneficiary dies before the owner, that beneficiary’s share passes down to their own descendants, typically their children. The share stays within that person’s branch of the family. If a parent names three children per stirpes and one of those children dies first, leaving two children of their own, the deceased child’s share is divided among those two grandchildren. The other two children keep their own shares unchanged. Each child’s family is treated as its own line, and the death of one child moves that child’s portion down to the next generation rather than away from the family branch.
Per capita, by contrast, means by the head. Under this treatment, if a beneficiary dies before the owner, that beneficiary’s share does not go to their descendants. It is redistributed among the surviving named beneficiaries. Using the same family, if a parent names three children and one dies first, the account is simply split between the two surviving children. The deceased child’s own children receive nothing, because this method looks only at the named beneficiaries who are still living and divides among them. The grandchildren in that branch are passed over entirely.
The consequence of the difference is the potential disinheritance of a whole line of grandchildren. A person who wanted each child’s family to receive an equal share, no matter which child outlived them, generally needs per stirpes to make that happen. A person whose form used the surviving-beneficiary approach, or who never made the election, may unintentionally leave one set of grandchildren with nothing simply because their parent died first.
This is where the practical hazard shows up, because the election is usually not automatic and the forms are not uniform. Per stirpes usually must be selected affirmatively. If it is not, the custodian’s default succession provisions control, and those provisions may send the deceased beneficiary’s share to the surviving named beneficiaries rather than to that beneficiary’s descendants. Custodians handle this differently, some default to dividing among survivors unless per stirpes is specifically requested, some offer per stirpes only if a person writes it in or checks a particular box, and some standard forms present the choice less clearly than others. A person cannot assume their form does what they would want. The only reliable approach is to ask the custodian directly what the default is, confirm whether per stirpes is available, and make the election explicitly. Writing something vague like naming all children without specifying the method can leave the account on whatever default the custodian uses, which may not be what the person intended.
Two features specific to retirement accounts raise the stakes. First, an IRA generally passes under the custodian’s beneficiary designation rather than the owner’s will. Whatever the will says, the account passes according to the beneficiary form, so a per stirpes wish expressed in a will does nothing if the beneficiary form says otherwise or is silent. Workplace plans also follow the plan’s own beneficiary procedures, but federal spousal protections may require the surviving spouse to receive the benefit unless the spouse properly consented to another beneficiary, so a person may not be free to name children on a workplace-plan form the same way they can on an IRA. Second, if no named or per stirpes beneficiary survives, the account passes under the custodian’s default succession rules. Depending on the agreement, that may mean a surviving spouse, then children, and ultimately the owner’s estate. An account that ends up paid to the estate generally loses the favorable payout treatment available to individual beneficiaries and can be exposed to probate, which is a poor outcome the designation was supposed to prevent.
Per stirpes also has limits worth understanding, because it is not a catch-all. It generally follows legally recognized descendants, meaning biological or legally adopted children and their descendants. An unadopted stepchild may not be included under the custodian’s definition, so anyone who intends to benefit a stepchild should name that person directly or confirm in writing that the designation reaches them. And if a deceased beneficiary leaves no qualifying descendants, the per stirpes instruction has no family branch to follow. The share then passes under the remaining language of the beneficiary designation and the custodian’s succession rules, often to the surviving beneficiaries at the same level. Per stirpes directs a share down a family line only when that line actually exists and the agreement recognizes it.
One more consideration cuts the other way. Per stirpes can solve the disinheritance problem while creating a different one, because it can bring grandchildren into the designation automatically. If a deceased child leaves young children, those grandchildren may inherit the retirement account directly, and a minor generally cannot control inherited assets personally. That can create custody and account-management questions, potentially requiring a guardian or other legally authorized person to manage the property, which is worth considering before the form is completed.
Picture a parent with two children, a son and a daughter, who splits an IRA between them equally and wants each child’s family to be provided for. The daughter has three children of her own, and the son has two. Assume the custodian’s form uses the common approach in which a deceased primary beneficiary’s share passes to their descendants only when per stirpes is selected, and otherwise goes to the surviving primary beneficiaries.
Under a per stirpes designation, if the daughter dies before the parent, her half of the IRA passes to her three children, who divide it among themselves, while the son keeps his half intact. Each branch of the family receives the same total share it would have received, with the daughter’s portion simply moving down to her children. The parent’s intention that both family lines be provided for is preserved.
Without that election, the same daughter’s death produces a very different result. Her half does not go to her three children. Instead the entire IRA passes to the surviving son, and the daughter’s three children receive nothing from the account. The parent may never have intended to disinherit those three grandchildren, but the failure to elect per stirpes produced exactly that outcome.
The resolution is treating the per stirpes versus per capita choice as a real decision rather than a box to skip. The question to answer before filling out any beneficiary form is simple. If one of the named beneficiaries dies first, should that person’s share go to their children, or should it be split among the other named beneficiaries? Per stirpes generally sends it down the family branch. The surviving-beneficiary approach spreads it among the survivors. Neither is universally correct, and the right choice depends on what the account owner wants for the descendants of a beneficiary who does not outlive them, and on what the custodian’s agreement actually provides.
The variables that decide the outcome are which method the designation actually uses, what the custodian’s form defaults to when the method is not specified, whether contingent beneficiaries are named as a backstop, whether the intended heirs are descendants the designation will actually reach, and whether bringing minor grandchildren in directly creates a management problem. Because the beneficiary form overrides the will for an IRA and because custodians handle the default and the definitions inconsistently, the reliable move is to confirm the actual designation on file directly with the custodian and to revisit it after any major family change, a death, a birth, a marriage, or a divorce. A beneficiary form that sat untouched for years may carry an outcome the owner would never choose today, and the fix takes only a few minutes once the person knows which question the form is really asking.
I write one of these every day, one retirement rule, explained in plain language and verified against the source. The daily email is free: subscribe here.
Full archive, worksheets, and search live at RetirementNewsRundown.com.
Disclaimer:
This article is for educational and informational purposes only. It is not tax, legal, or financial advice and does not create an advisor–client relationship. Always consult appropriate professionals regarding your specific situation.