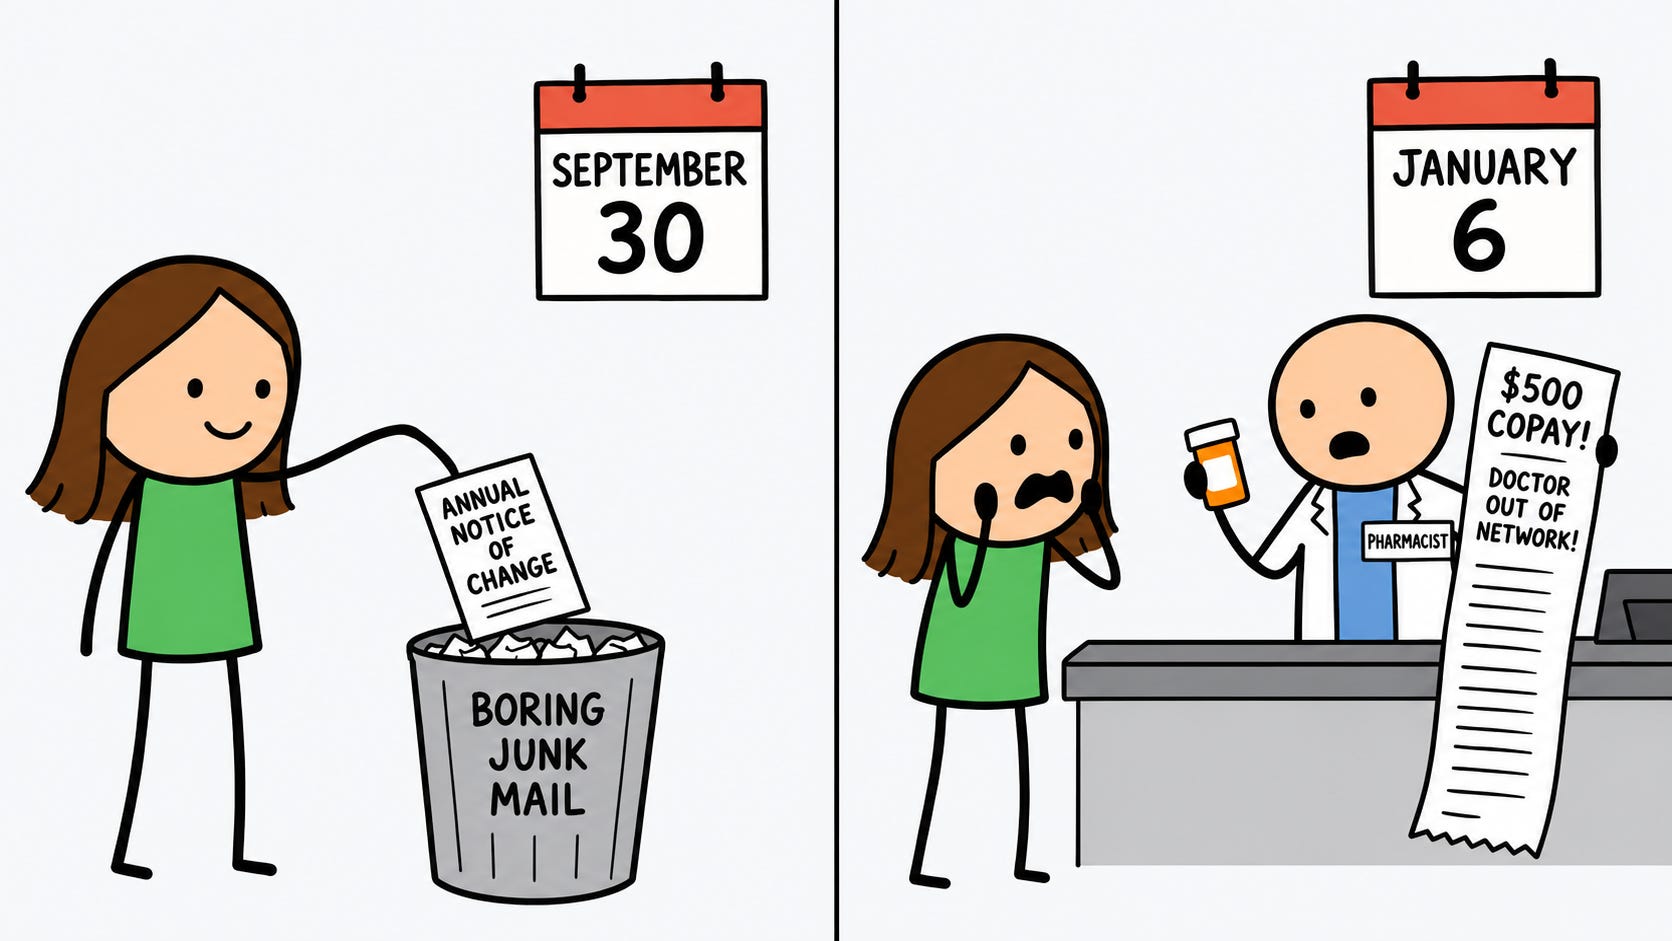
Every September, Medicare Advantage plans and Medicare drug plans send their members a document called the Annual Notice of Change. It arrives by September 30, printed or electronic, and it lists the changes to the plan that take effect on January 1. It tends to land in the same week as a dozen glossy plan brochures, which is unfortunate, because it is the one piece of mail in that stack written about the plan someone already has.
It also does not look urgent. No bill is attached, nothing needs a signature, and the headline news is often a premium change of a few dollars. So it goes into a drawer, and in January the pharmacy counter delivers the rest of the news in person.
The notice covers changes in coverage, costs, provider networks and service area that take effect in January. A second document, the Evidence of Coverage, follows by October 15, either as a printed copy or a notice explaining how to get it. The Evidence of Coverage is the full rulebook for the coming year. The Annual Notice of Change is the list of what moved. If neither shows up by early fall, the plan is the one to call.
People in Medicare Advantage plans and Medicare drug plans generally receive one. Original Medicare itself sends no Annual Notice of Change, and Medigap policies have their own notices and rules. The Part B premium can still change each year, and a Medigap insurer can still change its own premium, but those announcements arrive separately.
Reading the notice comes down to a handful of items, and most of them only matter in relation to the person holding it.
The premium is the obvious one and usually the least important. A plan with a slightly higher premium and a lower deductible can cost less over a year than one that held its premium steady.
Cost sharing is next: deductibles, copays and coinsurance for the services and drugs someone actually uses. A shift in what a specialist visit costs means nothing to a person who never sees a specialist and a great deal to someone who sees three.
For a Medicare Advantage plan, the yearly limit on out-of-pocket costs for Part A and Part B services is worth a look too. Each plan has its own, and the notice shows whether it moved.
The drug list matters most to people who take prescriptions. Plans sort covered drugs into tiers, and a drug that moves to a higher tier usually costs more at the counter even though it is still covered. A drug can also leave the list entirely. The notice is where a January change to someone’s own medications first appears. Plans can also adjust their drug lists during the year under Medicare’s rules, which is a separate subject for a separate day.
The provider network is the item people skip most often. Doctors and hospitals can join or leave a plan’s network from one year to the next. The notice can flag network changes, and the plan’s provider directory, or the plan itself, is where someone confirms whether a particular doctor or hospital will still be in network. Networks can also change during the year, and in that case the plan generally still has to provide access to qualified providers, though the member usually cannot switch plans over it.
Service area changes round out the list. A plan can shrink where it operates, and a Medicare Advantage plan can stop participating in Medicare altogether. When a plan leaves Medicare, its members have to join another Medicare Advantage plan or return to Original Medicare.
The timing is what gives the notice its value. It arrives by September 30. Open Enrollment runs October 15 through December 7, and anything changed in that window takes effect January 1. Everything in the notice also takes effect January 1, so the notice and the window line up exactly. Reading it in October leaves room to compare and switch. Reading it in January leaves the changes in force and, for most people, the plan locked in for the year.
There is one partial second chance. People in a Medicare Advantage plan can switch Advantage plans once, or return to Original Medicare, between January 1 and March 31, with the change effective the first of the month after the plan gets the request. Someone in Original Medicare with a separate drug plan has no equivalent. None of these are tax deadlines and none have a correction window. They are enrollment periods, and they come back on the calendar every year.
Dolores has a Medicare Advantage plan with drug coverage. Her Annual Notice of Change arrives on September 26, and she reads it in early October. The premium goes up slightly, and further down, her blood pressure medication moves from a lower tier to a higher one, which raises her copay. While she has the plan materials out, she also checks the provider directory and learns that her cardiologist will be out of network starting January 1.
She checks how her doctors and prescriptions fit other plans in her area and joins a different Medicare Advantage plan on November 18. The new plan starts January 1, and her cardiologist is in its network.
In the version where the notice goes into the drawer, Dolores finds out on January 6 when her pharmacy copay jumps, and again when her cardiologist’s office tells her it no longer takes her plan. Because she is in Medicare Advantage, she can still use the January to March window. She joins a different plan on February 10, and it starts March 1. January and February run under the old plan’s new terms, and that was her one change for the window.
Had Dolores been in Original Medicare with a separate drug plan, the January discovery would have left her with the new tier for the rest of the year, absent a special enrollment period.
Most of what makes the notice feel heavy is its length and its timing. A few lines in it actually apply to any one person: the premium, the costs for the care they use and their drugs, with a quick look at the provider directory for their doctors. Checking those in October takes less time than the brochures do, and the window to act on what turns up runs for weeks afterward.
What matters is reading it while there is still a window to use it. For someone whose notice has them weighing a move from Medicare Advantage back to Original Medicare, our Medigap guide covers how supplemental coverage fits that switch and when a policy can be bought.
I write one of these every day, one retirement rule, explained in plain language and verified against the source. The daily email is free: subscribe here.
Full archive, worksheets, and search live at RetirementNewsRundown.com.
Disclaimer
This article is for educational and informational purposes only. It is not tax, legal, or financial advice and does not create an advisor-client relationship. Always consult appropriate professionals regarding your specific situation.