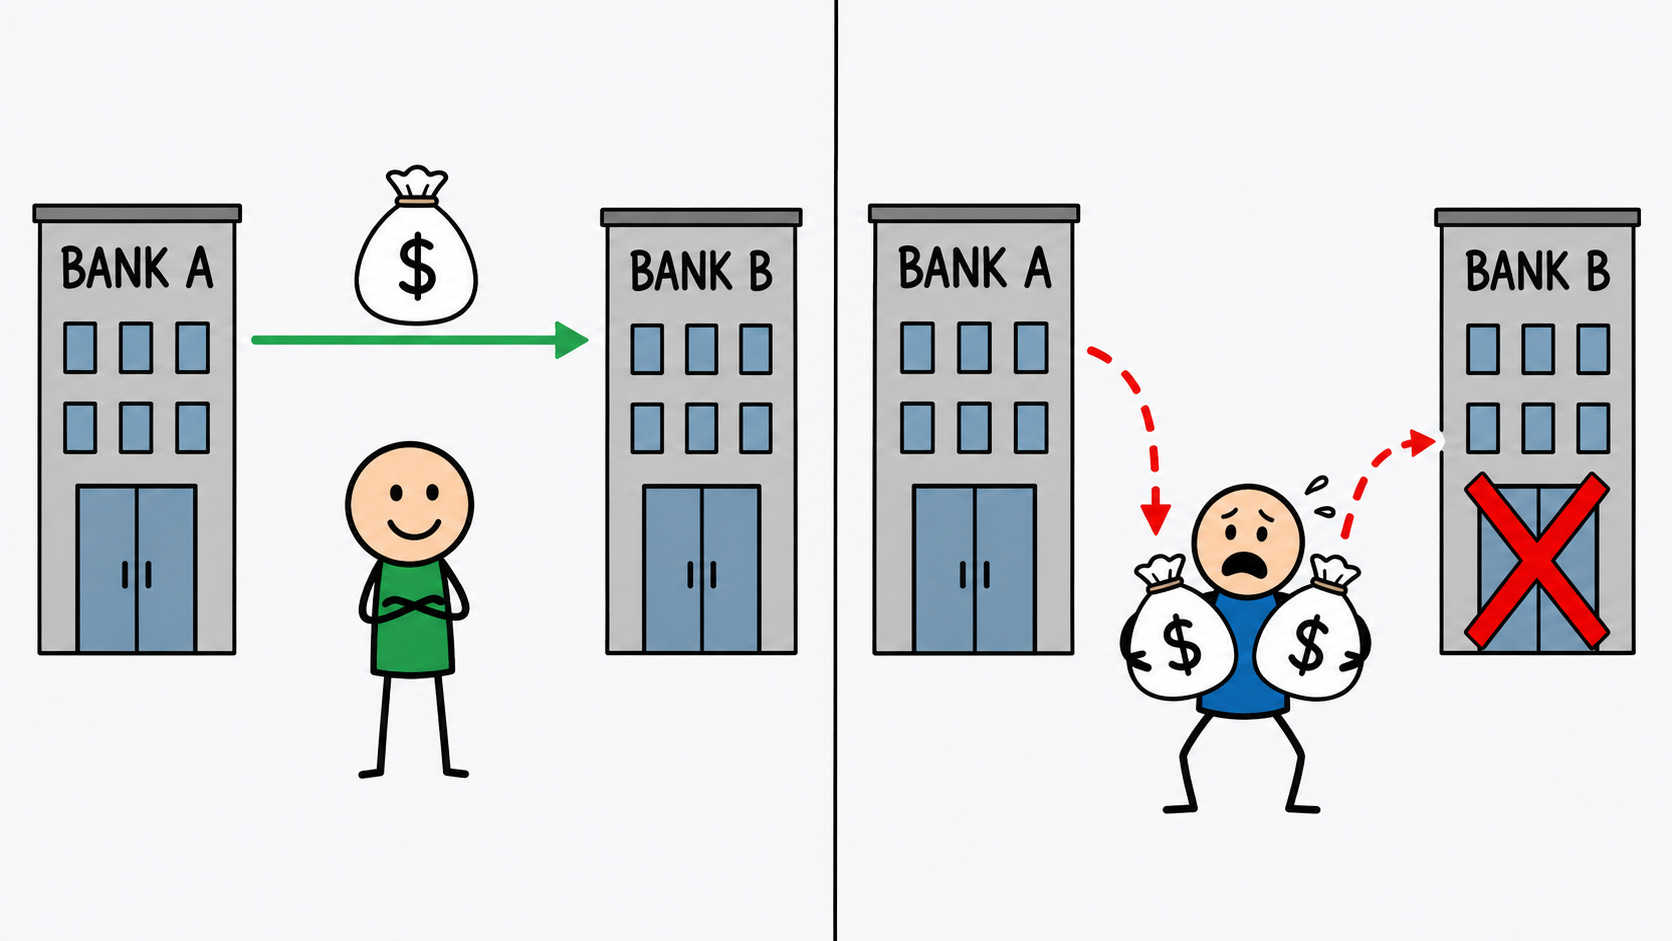
Retirement money can move between institutions through two separate mechanisms. One is a trustee-to-trustee transfer, where the money goes straight from one custodian to another. The other is a rollover, where the money is distributed to the owner and then redeposited. The mechanism used determines which limits and deadlines apply.
The two words get used as if they mean the same thing. A person says they want to transfer a 401(k) and actually triggers a rollover, or asks to roll over an IRA and actually receives a transfer. The labels get swapped in casual conversation without consequence, right up until the difference produces a tax bill.
Someone decides to consolidate two IRAs into one. They assume any method of getting the money from account A to account B is fine, because the money is theirs and the destination is another retirement account. Whether that holds depends entirely on how the money makes the trip.
A transfer moves money directly between two custodians. The funds go from one IRA to another IRA of the same type without the account owner ever taking possession. The money leaves one custodian and lands at the other, and very little happens for tax purposes. A direct transfer between like IRAs is generally not reported as a distribution, and no 60-day clock applies because the money never leaves the IRA system.
The defining feature of a transfer is the absence of limits. A person can move IRA money by transfer as many times as they want in a year. There is no cap, no waiting period, and no deadline, because a transfer is not a distribution and does not need to be completed within any window.
A rollover works differently. In the version that causes trouble, the account owner receives the distribution, takes possession of the money, and has limited time to redeposit it into an eligible retirement account. This is the 60-day rollover. The owner has 60 calendar days from the date of receipt to complete the redeposit. Miss the 60 days, and the distribution is no longer a rollover. It becomes taxable income, subject to ordinary tax and, for an owner under 59½ without an exception, the 10% early withdrawal penalty.
The 60-day rollover carries a second rule that surprises people. An individual can complete only one IRA-to-IRA 60-day rollover in any 12-month period. The limit runs from the date the distribution was received, not by calendar year, and it applies across all of a person’s IRAs combined. A second IRA-to-IRA 60-day rollover inside that window is not valid. The amount becomes a taxable distribution, and the money redeposited becomes an excess contribution exposed to the 6% excise tax until corrected.
Some moves look like rollovers but escape the once-per-year limit. A direct rollover from an employer plan such as a 401(k) to an IRA sends the money straight to the receiving custodian without the owner taking possession. A Roth conversion is also outside the once-per-year limit. The rule applies specifically to 60-day rollovers between IRAs.
Employer plans carry one more caution. A distribution paid to the participant rather than sent directly to the new custodian triggers a mandatory 20% federal withholding, which means rolling over the full amount requires replacing that withheld portion out of pocket. A direct rollover avoids the problem entirely.
One category of money cannot be rolled over at all. A required minimum distribution is not an eligible rollover amount, and for an owner of RMD age, the first dollars to leave the IRA each year are deemed to satisfy that year’s RMD. Trying to redeposit that amount produces a failed rollover, a taxable distribution, and an excess contribution. The RMD has to come out and stay out before any remaining balance can take a 60-day trip.
What happens if a transfer is done later rather than sooner? Nothing, because a transfer has no deadline. What happens if a rollover redeposit lands after 60 days? The rollover fails unless the owner qualifies for relief under the IRS waiver or self-certification rules, which cover specific events beyond the owner’s control such as a financial institution error. That is a correction path, not a planning strategy.
Marcus has three IRAs at three custodians and wants them in one place. In February the first custodian sends him a check, which he redeposits into the destination IRA nine days later. That is a valid 60-day rollover.
In May he does the same with the second IRA, again well within 60 days. But this is his second IRA-to-IRA 60-day rollover within a 12-month period, and the rule allows only one. The May rollover is not valid, so that distribution is taxable income and the redeposited amount is an excess contribution accruing the 6% excise tax.
Had Marcus instead asked each custodian to send the money directly to the destination IRA, every move would have been a transfer. Transfers have no annual limit, so all three accounts could have been consolidated in one week with no tax consequence.
The difference between a rollover and a transfer comes down to one question. Does the money pass through the account owner’s hands? If the funds move directly between custodians, it is a transfer, unlimited and free of deadlines. If the owner receives the money and redeposits it, it is a 60-day rollover, carrying the 60-day clock and the once-per-year limit.
For most account consolidations, the transfer is the cleaner method by a wide margin. No annual cap, no 60-day countdown, no risk of an accidental taxable event. The 60-day rollover has legitimate uses, but it is the method that turns a routine move into a tax problem when used twice without knowing the rule.
Anyone moving retirement money can avoid this entire category of mistakes by asking the custodian to move the funds directly. Money that never touches the owner’s hands cannot miss a deadline or trip a limit. The label matters less than the mechanics behind it.
I write one of these every day, one retirement rule, explained in plain language and verified against the source. The daily email is free: subscribe here.
Full archive, worksheets, and search live at RetirementNewsRundown.com.
Disclaimer This article is for educational and informational purposes only. It is not tax, legal, or financial advice and does not create an advisor–client relationship. Always consult appropriate professionals regarding your specific situation.