When a person removes an excess IRA contribution before the deadline to avoid the penalty, they cannot simply pull out the exact dollar amount they overcontributed. They have to remove that excess plus, or minus, the earnings it generated while it sat in the account. That earnings figure has a name, net income attributable, and it is calculated by a specific formula the IRS prescribes. Most people never see this math because the custodian runs it, but understanding it matters, because it determines how much actually comes out, whether the correction is done right, and how much of the withdrawal is taxable. The formula also holds a surprise that trips people up, since it is based on the whole account’s performance rather than on what the excess dollars themselves did.
Net income attributable, usually shortened to NIA, is the amount of gain or loss that gets allocated to an excess contribution for the period it was in the account. When a person removes an excess contribution in a timely correction, the rule requires the excess to leave together with the net income attributable to it. If the account gained value during that period, the NIA is positive, and the person removes the excess plus that gain. If the account lost value, the NIA is negative, and the person removes the excess minus that loss, which means less than the original excess comes out.
The formula itself, set out in the Treasury regulations, is a rate-of-return calculation. The net income attributable equals the excess contribution multiplied by the account’s overall rate of change over the relevant period. Written out, it is the excess contribution times the difference between the adjusted closing balance and the adjusted opening balance, divided by the adjusted opening balance. That middle piece, the closing balance minus the opening balance divided by the opening balance, is simply the percentage the account grew or shrank while the excess was in it. Multiplying the excess by that percentage gives the share of the account’s gain or loss that belongs to the excess.
The two balances have precise definitions that matter. The adjusted opening balance is the fair market value of the IRA immediately before the computation period begins, plus contributions, transfers, and recharacterizations that went into the account during that period, including the contribution being corrected. The adjusted closing balance is the fair market value immediately before the corrective distribution, plus distributions, transfers, and recharacterizations that left the account during the period. The computation period runs from just before the excess went in to just before it comes out. Getting these two figures right is the whole calculation, because everything else is arithmetic.
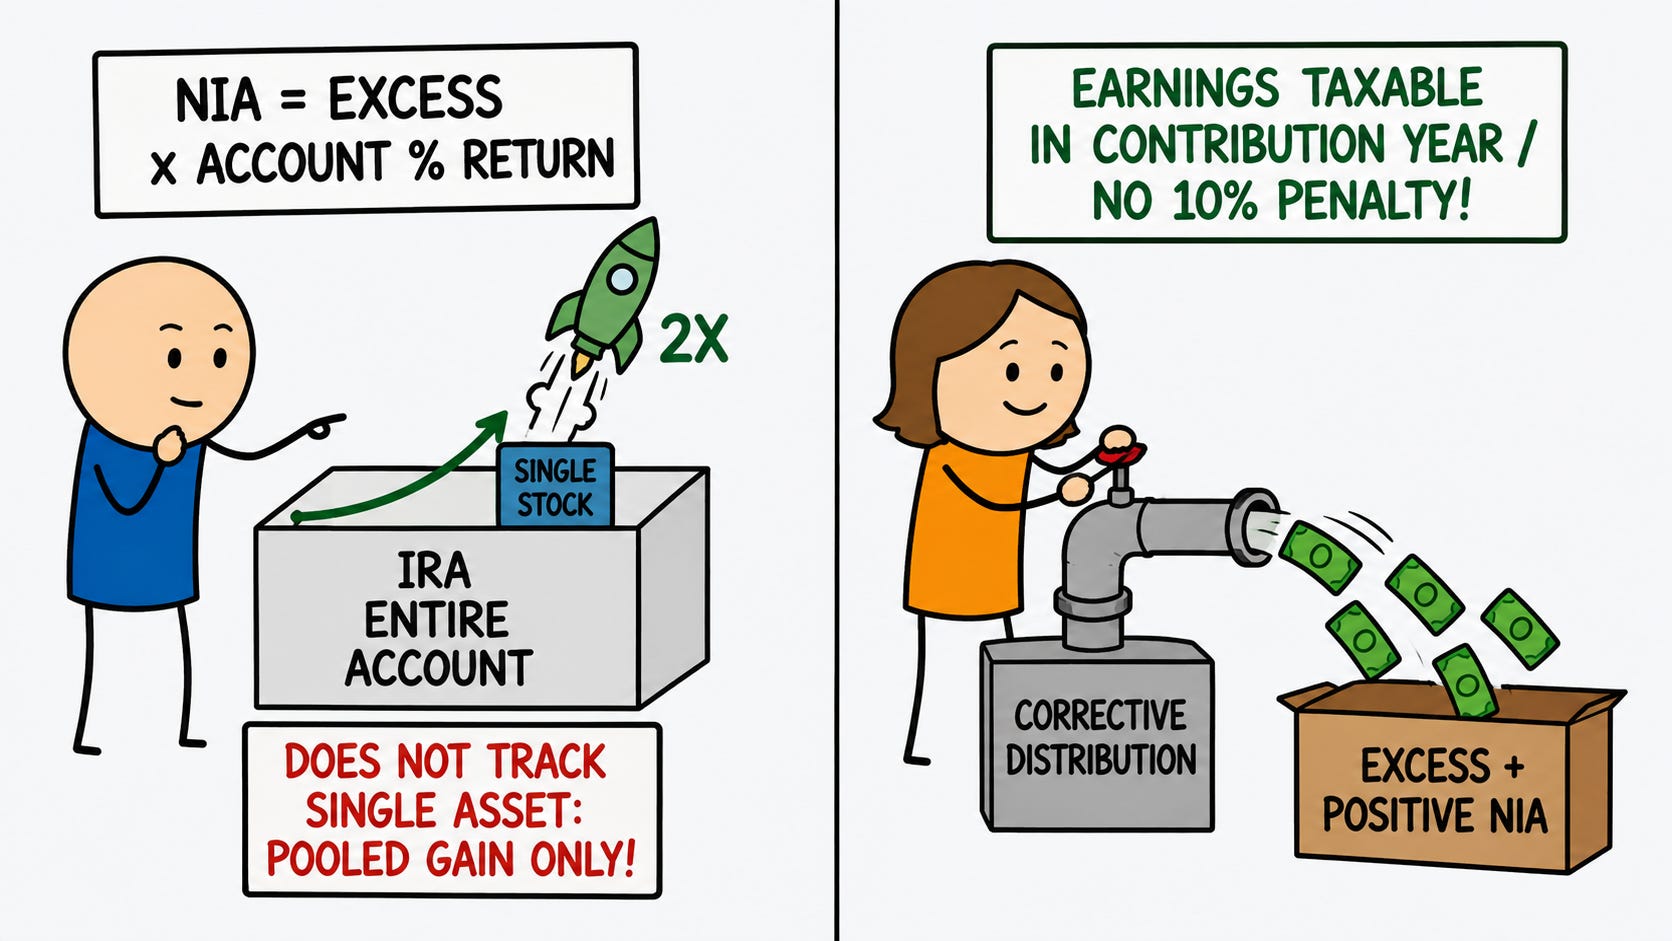
Here is the feature that surprises people most, and it is worth stating plainly. The calculation uses the performance of the entire IRA that received the contribution, not the performance of whatever the excess dollars were specifically invested in. If a person owns several IRAs, the accounts are not combined for this calculation. The NIA is figured using only the IRA that actually received the contribution being corrected, and that same IRA is the one that distributes the correction. So if a person contributed an excess and used it to buy a single stock that happened to double, but the rest of that account was flat, the NIA does not reflect that the stock doubled. It reflects the whole account’s overall return, which was modest. The reverse is also true. If the excess bought a stock that crashed while the rest of the account soared, the NIA reflects the account’s overall gain, not the crash. The regulation deliberately allocates a proportional share of the entire account’s earnings to the excess, rather than tracing the specific dollars. This means a person cannot game the result by pointing to what the excess money specifically bought, and it also means the NIA can be positive even when the specific investment lost money, or negative even when the specific investment gained.
The direction of the NIA changes what happens on the way out. A positive NIA, from an account that gained, means the gain portion is taxable. That gain is taxable in the year the contribution was made, not the year it is withdrawn, and under the current rules it is no longer subject to the ten percent early withdrawal penalty for a person under 59.5 when it is a timely correction. A negative NIA, from an account that lost value, means the person removes less than the excess, and there is no deduction for that loss. The loss simply reduces the amount that has to come out to fix the excess.
This same formula governs recharacterizations, not just withdrawals. When a person recharacterizes a contribution from one type of IRA to another, the amount that moves over is the contribution plus or minus its net income attributable, calculated exactly the same way. So the NIA is not only about pulling money out. It also determines how much moves when a Roth contribution is recharacterized to a traditional IRA, which is one of the correction paths for an excess.
One practical point ties it together. The custodian almost always performs this calculation, because they hold the account values and process the distribution. But the formula is public, and understanding it serves two purposes. It lets a person check that the custodian computed it correctly, which matters because an error in the NIA can leave the correction incomplete or create a tax reporting mismatch. And it helps in the more complicated situations, where money was transferred in or out during the period, or where multiple contributions are involved, since those adjustments are exactly what the opening and closing balance definitions are built to capture. This calculation applies when a contribution is being returned under the timely-correction rules, generally by the tax-return due date including extensions, with additional six-month relief available in certain cases when the original return was timely filed. Once that timely-correction window is truly closed, later excess-contribution corrections follow different rules and generally do not use this earnings calculation.
Walk through a simple case. Suppose a person made an excess contribution of one thousand dollars. Immediately before that contribution, their IRA was worth twenty thousand dollars. So the adjusted opening balance is twenty one thousand dollars, the twenty thousand plus the one thousand excess that went in. By the time they correct it, the account has grown, and immediately before the corrective distribution it is worth twenty three thousand one hundred dollars, with no other contributions or distributions in between, so that is the adjusted closing balance.
The account’s rate of change over the period is the closing minus the opening, divided by the opening, which is twenty three thousand one hundred minus twenty one thousand, divided by twenty one thousand, or ten percent. The net income attributable is the excess times that rate, one thousand dollars times ten percent, which is one hundred dollars. So the person removes one thousand one hundred dollars total, the one thousand excess plus one hundred of attributable earnings, and that one hundred dollars of earnings is the taxable portion, taxed in the year the contribution was made.
Now change the account’s performance. Suppose instead the account fell during the period, so the adjusted closing balance came out lower than the adjusted opening balance, a negative rate of return. Applying that negative rate to the one thousand dollar excess produces a negative net income attributable, say a loss of eighty dollars. In that case the person removes only nine hundred twenty dollars to correct the excess, the one thousand reduced by the eighty dollar attributable loss. Nothing is taxable, because there were no earnings, and the loss is not deductible. The same excess produced a different withdrawal amount purely because the account performed differently, and in both cases the whole account’s return, not the specific investment, drove the result.
The resolution is understanding that correcting an excess contribution timely means removing the excess adjusted by its net income attributable, and that this figure comes from a fixed formula based on the entire account’s performance over the period the excess was held. The formula multiplies the excess by the account’s rate of gain or loss, using the adjusted opening and closing balances that the regulation defines. A gain makes the removal larger and creates a taxable earnings amount for the contribution year. A loss makes the removal smaller and creates no deduction.
The variables that determine the NIA are the account’s value immediately before the excess went in, its value immediately before the correction comes out, any contributions or distributions in between that adjust those balances, and the size of the excess itself. Because the calculation uses the whole account that received the contribution rather than the specific investment, the result can surprise a person who assumed the earnings would track what the excess dollars actually bought. The custodian usually runs the numbers, but knowing how the formula works lets a person confirm the figure is right and understand why the amount leaving the account is more, or less, than the excess they put in. It is the same calculation whether the excess is being withdrawn or recharacterized, which makes it the common engine behind the timely correction of any excess contribution.
I write one of these every day, one retirement rule, explained in plain language and verified against the source. The daily email is free: subscribe here.
Full archive, worksheets, and search live at RetirementNewsRundown.com.
Disclaimer
This article is for educational and informational purposes only. It is not tax, legal, or financial advice and does not create an advisor–client relationship. Always consult appropriate professionals regarding your specific situation.