It usually starts with a harmless sentence.
“I’ll deal with it after tax season.”
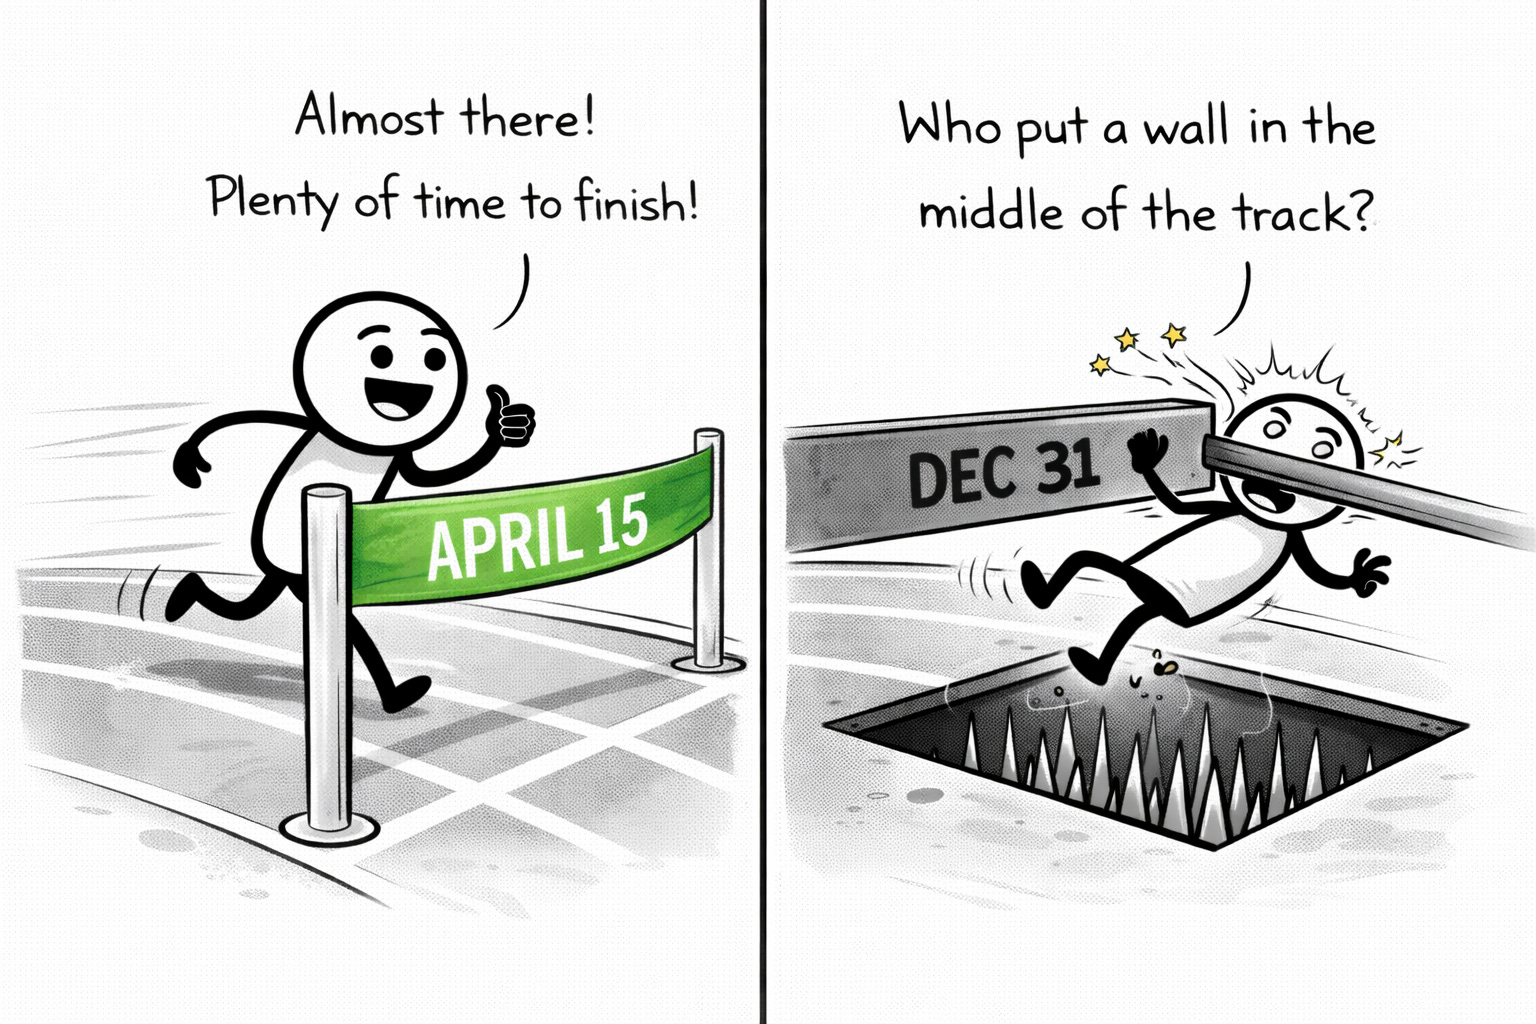
March shows up every year with that exact promise. Plenty of people feel productive. Forms are coming in. Numbers are getting gathered. There is a comforting illusion that time is still flexible. After all, April 15 is right there on the calendar, blinking patiently.
The problem is that March is when a lot of retirement and tax decisions quietly lock into place. Nothing dramatic happens. No alarms go off. No warning letters arrive. The system just keeps moving, and when April shows up, people discover that what they thought was a pause was actually a closing door.
By the time panic sets in, most of the damage has already been done.
Here is the uncomfortable rule March exposes.
Many retirement and tax rules are governed by calendar years, not filing deadlines. Once December 31 passes, certain decisions are final even if the paperwork is still open. March sits in the gap where people assume flexibility exists, but for many items, the window already closed months ago.
Traditional IRA and Roth IRA contributions are the rare exception. Those can usually be made up until the tax filing deadline. That one fact trains people to assume the same flexibility applies everywhere else. It does not.
Roth conversions are strictly calendar year events. If the conversion did not happen by December 31, it belongs to the next year. March cannot fix that. Filing extensions do not fix that. There is no correction window because nothing was done incorrectly. It simply was not done at all.
Required minimum distributions work the same way. If an RMD was missed in December, March is not a grace period. The distribution is late. The penalty clock already started. Fixing it later may reduce penalties, but it does not rewind the calendar.
Employer plan deadlines add another layer of confusion. Some plans allow contributions after year end, but only if the plan existed by December 31. If the plan was not opened in time, March cannot retroactively create it. Extensions may allow funding, but only for plans that were already legally in place.
March is where calendar-year rules collide with filing-year assumptions. Once you cross that line, options narrow fast.
A real example makes this clearer.
Imagine someone who left a job in June of last year and rolled their 401(k) into a traditional IRA. In December, they planned to convert part of it to a Roth. They decided to wait until tax forms arrived so they could estimate the tax impact accurately. March feels like a reasonable time to revisit the idea.
On March 10, they call to ask about converting $40,000 “for last year.”
That conversion cannot happen. The calendar closed on December 31. If they convert now, it is a conversion for the current year. That changes everything. It affects a different tax year, a different set of income numbers, and potentially a different Medicare premium bracket two years from now.
Nothing went wrong operationally. No rule was broken. The system is doing exactly what it was designed to do. The opportunity simply expired.
Now compare that to an IRA contribution. If that same person wants to make a traditional IRA contribution for last year and they are eligible, March is still fine. The tax filing deadline governs that contribution. Even an extension may buy more time.
Two actions. Two very different clocks. One flexible. One unforgiving.
March is where people discover they assumed the wrong clock was running.
Corrections follow a similar pattern.
If too much was contributed to an IRA, there is a correction window. That excess can often be removed by the tax filing deadline to avoid penalties. March still offers room to act.
If the wrong account received a rollover, there may be a 60 day correction window depending on how it was handled. By March, that window may already be closed.
If a required distribution was missed, March does not erase the miss. It only allows damage control. The distribution can still be taken, but penalties may apply unless relief is requested.
What happens if these things are done later instead is always the same answer. The calendar does not bend. Later means different tax years, penalties, or permanent loss of an option.
This is why March feels so stressful even when nothing new is happening.
It is not the month of deadlines. It is the month of realization.
People finally slow down enough to look closely. When they do, they see which doors are still open and which ones closed quietly while everyone was celebrating the holidays.
The system does not punish procrastination with noise. It punishes it with silence.
Here is the resolution most people need.
March is not about scrambling to fix everything. It is about understanding what is still changeable and what is not. Fear comes from thinking everything is broken. Calm comes from knowing exactly where you stand.
Some moves are gone. That does not mean the year is ruined. It means the focus shifts forward instead of backward.
If something is still governed by a filing deadline, March offers time. If something was governed by the calendar year, March offers clarity, not flexibility.
Once you understand which clock applied, the anxiety drops fast. You stop chasing fixes that no longer exist and start working with the reality that does.
March is not the villain. It is the mirror.
I write one of these every day, one retirement rule, explained in plain language and verified against the source. The daily email is free: subscribe here.
Disclaimer
This article is for educational and informational purposes only. It is not tax, legal, or financial advice and does not create an advisor–client relationship. Always consult appropriate professionals regarding your specific situation.